
December always arrives faster than we expect. Between festivals, year-end work and holiday plans, money tasks slip down the list. That is risky, because some tax deadlines in India fall in December, and missing them can cost you fees and interest.
In this guide, we cover the key financial tasks before the end of 2026 that Indian taxpayers should not ignore. You will learn what to do, by when, what a delay can cost, and how to finish each task without stress. Let’s get started.
In This Article
ToggleHighlight key
- 15 December 2026: Third advance tax instalment deadline for eligible taxpayers.
- 31 December 2026: General deadline for filing a belated ITR for FY 2025–26 (AY 2026–27).
- 31 March 2027: General revised-return deadline for AY 2026–27, subject to applicable rules.
- FY 2026–27: The Income-tax Act, 2025 applies from 1 April 2026.
- Reviewing your tax regime, nominees, and account details can help you avoid common financial problems.
Always confirm deadlines and applicable requirements through the official Income Tax Department website.
Why Year-End Financial Planning Matters in 2026
Two financial years are relevant to taxpayers during this period.
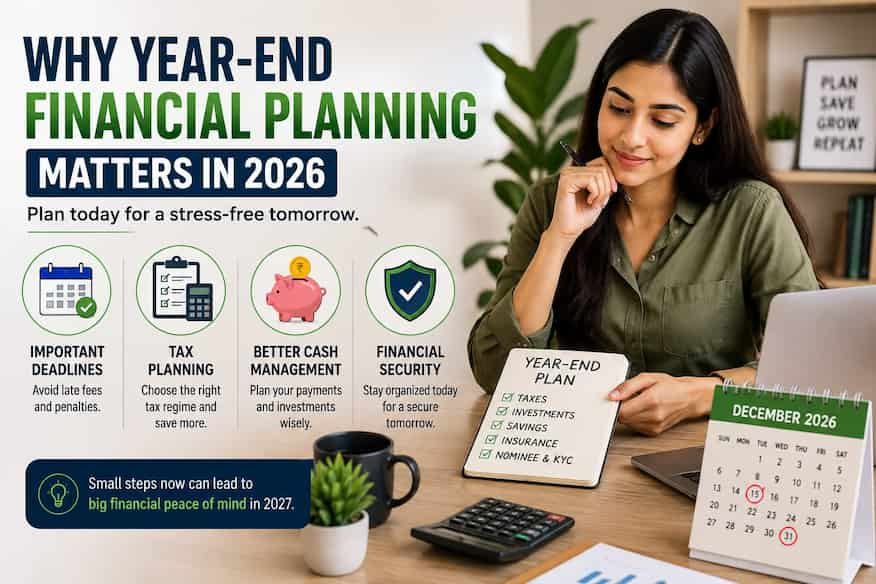
FY 2025–26 (AY 2026–27): This refers to income received between 1 April 2025 and 31 March 2026. Eligible taxpayers who missed their original ITR deadline may still be able to file a belated return.
FY 2026–27: This covers income earned from 1 April 2026 to 31 March 2027. The Income-tax Act, 2025 came into force on 1 April 2026, introducing a new legislative framework for income tax.
Understanding which financial year applies to your income is essential because deadlines, deductions, and tax provisions can differ.
The 4 Financial Tasks Before the End of 2026
1. File or Correct Your Income Tax Return
Deadline: Generally 31 December 2026 for a belated return for AY 2026–27.
If you missed your applicable original ITR filing deadline for FY 2025–26, check whether you can file a belated return.
For many individual taxpayers, the original deadline was 31 July 2026, although different deadlines may apply to certain categories of taxpayers.
What Happens If You File Late?
Late filing can lead to the following consequences:
- Late filing fee: Generally ₹5,000 if total income exceeds ₹5 lakh, or ₹1,000 if total income does not exceed ₹5 lakh, subject to applicable provisions.
- Interest: Interest may apply to unpaid tax under the relevant rules.
- Loss restrictions: Missing the applicable deadline can prevent you from carrying forward certain losses, subject to statutory exceptions.
For instance, if your annual income totals ₹8 lakh and ₹20,000 in tax remains unpaid, you could face a late filing penalty and relevant interest charges along with the pending tax amount.
The exact amount depends on your circumstances and payment dates. Use the official tax portal or consult a Chartered Accountant to calculate your liability.
Already Filed Your Return?
If you discover an error after filing your ITR, you may be eligible to submit a revised return.
For AY 2026–27, the general revised-return deadline is 31 March 2027, subject to applicable provisions. An additional fee may apply when a revised return is filed after 31 December 2026.
Before revising your return, check your:
- Form 26AS
- Annual Information Statement (AIS)
- Taxpayer Information Summary (TIS)
- Form 16, where applicable
- Bank interest and investment records
Correcting mistakes early gives you more time to review your records and complete the necessary formalities.
Official source: Income Tax Department e-Filing Portal
2. Pay Your Third Advance Tax Instalment
Deadline: 15 December 2026.
Advance tax allows eligible taxpayers to pay their income tax in instalments throughout the financial year.
It generally applies when your estimated tax liability, after reducing TDS and eligible credits, is ₹10,000 or more.
Freelancers, consultants, landlords, business owners, and investors with taxable income may need to check their advance tax obligations.
Advance Tax Schedule for FY 2026–27
Deadline: 15 December 2026.
Advance tax allows eligible taxpayers to pay their income tax in instalments throughout the financial year.
It generally applies when your estimated tax liability, after reducing TDS and eligible credits, is ₹10,000 or more.
Freelancers, consultants, landlords, business owners, and investors with taxable income may need to check their advance tax obligations.
| Due Date | Cumulative Payment Target |
|---|---|
|
15 June 2026 |
15% |
|
15 September 2026 |
45% |
|
15 December 2026 |
75% |
|
15 March 2027 |
100% |
These are the general instalment targets for eligible taxpayers who are not covered by a special payment schedule.
Simple Example
Suppose your estimated advance tax liability after TDS and eligible credits is ₹80,000.
By 15 December, your cumulative payment target would generally be:
₹80,000 × 75% = ₹60,000.
If you have already paid ₹36,000, you would need another ₹24,000 to reach the 75% target.
This is a simplified illustration. Interest may apply if you fail to pay the required instalments on time. The actual calculation depends on the applicable provisions, shortfall, and period of default.
Who May Not Need to Pay Advance Tax?
Salaried employees whose tax liability is fully covered by TDS may not need separate advance tax payments.
Resident senior citizens aged 60 or above who do not have income from a business or profession are generally exempt. Eligible taxpayers using presumptive taxation provisions may also follow a different payment schedule.
If you receive capital gains, rental income, or freelance earnings, review your tax liability carefully.
3. Review Your Tax Regime and Plan Tax Savings
You do not necessarily have to finalise every tax-planning decision in December. However, reviewing your income and deductions now can prevent a last-minute rush in March 2027.
For FY 2026–27, the new tax regime is generally the default regime for eligible individuals. The old regime may allow certain deductions and exemptions that are unavailable under the new regime.
New Tax Regime
The new regime generally offers lower tax rates across its applicable income slabs but restricts many deductions and exemptions.
Eligible salaried taxpayers may benefit from the applicable standard deduction. Eligible resident individuals may also qualify for a tax rebate, subject to the applicable conditions.
However, the final tax liability depends on your income, the nature of that income, and your eligibility for tax benefits.
Old Tax Regime
The old regime generally allows certain deductions and exemptions, depending on eligibility. These may include:
- Eligible savings and investments.
- Health insurance premiums.
- Qualifying home loan interest.
- Other permitted deductions.
For FY 2026–27, Section 123 of the Income-tax Act, 2025 allows certain deductions on qualifying savings and investments, subject to applicable conditions and prescribed limits.
How to Choose the Right Regime
Follow these simple steps:
- Estimate your total annual income.
- Calculate your eligible deductions and exemptions.
- Compare your tax liability under both regimes, if you are eligible to choose.
- Consider your overall financial goals before making investments.
- Use the official tax calculator or consult a qualified tax professional.
Do not purchase an unsuitable financial product merely to save tax. Investment decisions should also consider risk, liquidity, costs, and your long-term goals.
4. Update Your Nominees and KYC Details
There is no universal government deadline requiring everyone to complete these tasks by 31 December 2026. However, reviewing your financial records before the year ends is a useful habit.
Check Your Nominees
Review nomination details for your:
- Bank accounts.
- Mutual fund investments.
- Demat accounts.
- Eligible provident fund accounts.
- Life insurance policies.
If your family circumstances have changed, check whether your nominee details still reflect your intentions.
Nomination rules differ across financial products, so understand the applicable requirements before making changes.
Update Your KYC Details
KYC means Know Your Customer. Financial institutions use KYC information to maintain customer records.
Check your registered address, mobile number, email address, PAN, and other required details. Update incorrect information through the relevant bank or financial institution.
Accurate information can help reduce delays in account servicing and verification.
Check Your PAN–Aadhaar Status
PAN–Aadhaar requirements depend on your circumstances and the applicable rules.
A specific deadline of 31 December 2025 applied to certain individuals who obtained PAN using an Aadhaar enrolment ID. It was not a universal deadline for every PAN holder.
If your PAN is inoperative or you are unsure whether linking is required, check your status on the official Income Tax Department portal.
Important Financial Deadlines at a Glance
| Date | Financial Task |
|---|---|
|
15 December 2026 |
Third advance tax instalment |
|
31 December 2026 |
General deadline for a belated ITR for AY 2026–27 |
|
15 March 2027 |
Final general advance tax instalment |
|
31 March 2027 |
General revised-return deadline for AY 2026–27 |
These dates are subject to applicable rules and official extensions. Check the requirements relevant to your circumstances before making a payment or filing a return.
Common Financial Mistakes to Avoid
- Waiting until the last day: Technical issues or missing documents can cause delays. Complete eligible tasks early.
- Guessing your advance tax: Estimate income using salary records, bank statements, investment gains, and TDS information.
- Ignoring AIS: Compare your tax records with the information available in your Annual Information Statement.
- Choosing a tax regime without comparing: Calculate your tax under both eligible regimes before deciding.
- Confusing tax payment with return filing: Paying outstanding tax does not automatically complete your ITR filing obligations.
Conclusion
Completing your financial tasks before the end of 2026 can help you enter 2027 with fewer worries.
Review your income tax return, check your advance tax obligations, compare your tax-regime options, and update your nominees and KYC details.
Not every task has a December deadline, and the consequences of missing a deadline depend on the applicable rules. Therefore, verify important details through official sources and seek professional help when necessary.
Start early, keep your documents organised, and make informed financial decisions.
Disclaimer: This article is for general educational purposes only. It is not tax, legal, or investment advice. Tax laws, deadlines, fees, and eligibility conditions may change. Confirm your circumstances through the official Income Tax Department portal or consult a qualified Chartered Accountant.
Article Sources
- Advance Tax Payment Rules: Income Tax Department – Tax Payments
- PAN–Aadhaar Linking: Income Tax Department – Link Aadhaar
- Section 123 and Tax Deductions: Income Tax Department – Set-off and Carry-forward FAQs
FAQ's
What is the last date to file an ITR for FY 2025–26?
The general deadline for an eligible belated return for AY 2026–27 is 31 December 2026, subject to applicable provisions and official extensions. Late fees and interest may apply.
Do salaried employees need to pay advance tax?
Usually not if their tax liability is fully covered by TDS. Additional taxable income, such as capital gains or rental income, may create an advance tax obligation.
What happens if I miss the 15 December advance tax deadline?
Interest may apply under the applicable provisions. The amount depends on the payment shortfall and period of default.
Can I revise my income tax return after filing?
An eligible return for AY 2026–27 can generally be revised by 31 March 2027, subject to applicable conditions. Check whether an additional fee applies to your case.
Is Section 80C still available in FY 2026–27?
The Income-tax Act, 2025 applies from 1 April 2026. Section 123 provides for specified deductions relating to eligible savings and investments, subject to its conditions and limits. Check the applicable tax regime and current provisions before claiming a deduction.
My name is Subodh Kumar, and I am a finance blogger at Financemantraa.com with a strong interest in personal finance, investing, and financial research spanning 4–5 years.
I enjoy researching financial topics and explaining complex money concepts in simple, easy-to-understand language. My areas of interest include stock market basics, IPOs, mutual funds, financial planning, insurance, saving strategies, and wealth building.
Through Financemantraa.com, I aim to help readers improve their financial knowledge, understand investment concepts, and make informed financial decisions. I focus on creating practical, beginner-friendly guides that make personal finance easier to understand and apply in everyday life.
I believe that financial education and smart money habits can help people work toward long-term financial stability. My goal is to make reliable, accessible, and informative financial content available to everyone.
Disclaimer: The information published on Financemantraa.com is for educational and informational purposes only. It should not be considered professional financial or investment advice.