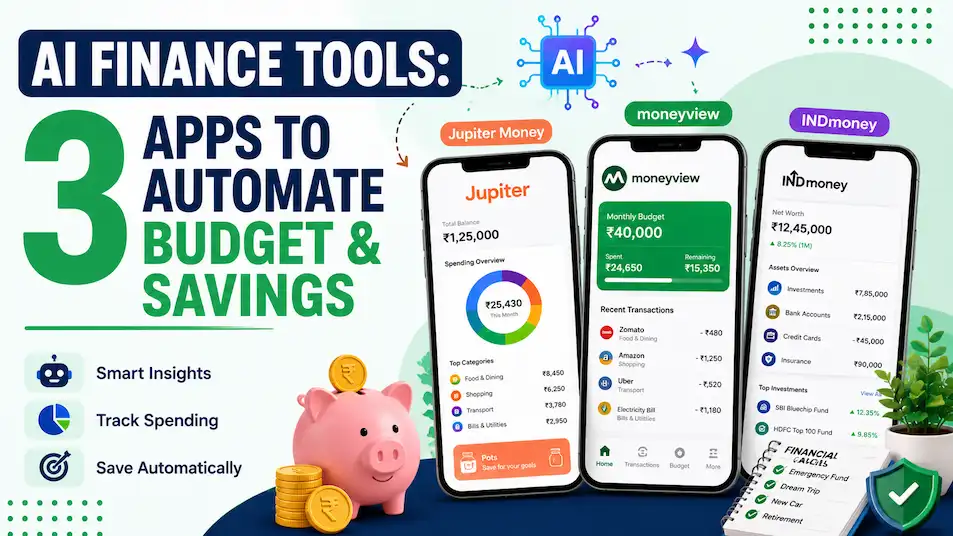
Most people don’t fail at budgeting because they don’t care. They fail because tracking every rupee by hand gets boring fast. This is where AI finance tools can help. They use automation and smart insights to track your transactions, sort them into categories, and help you save, so you do less manual work.
In this guide, we will look at three popular finance apps available in India: Jupiter Money, Moneyview, and INDmoney. You will learn what each one does, where it falls short, and how to set up automatic budgeting and savings step by step.
In This Article
ToggleHighlight key
- AI budgeting tools and automated finance apps sort your spending, so you don’t need to type in every expense.
- Jupiter Money offers spending categorisation, linked account tracking, and savings Pots.
- Moneyview is a simple tracker that reads transaction-related SMS messages with your permission.
- INDmoney suits people who want expenses, investments, and net worth in one place.
- Automation helps, but you still decide your budget and financial goals.
- Features, pricing, and privacy policies can change, so check each app before you sign up.
What Are AI Finance Tools?
AI finance tools are apps that use software intelligence, automation, and data analysis to manage everyday money tasks. In simple words, they do three jobs:
Collect data: They read bank SMS alerts or linked accounts to understand what you spend.
Sort it: They label each payment as food, travel, bills, shopping, and so on.
Guide you: They show spending trends, send reminders, or provide insights about your financial habits.
A word of caution: the “AI” label is used loosely. In many apps, it simply means automatic categorisation and smart insights, not a robot managing your money. That is still useful, as long as you know what you are getting.
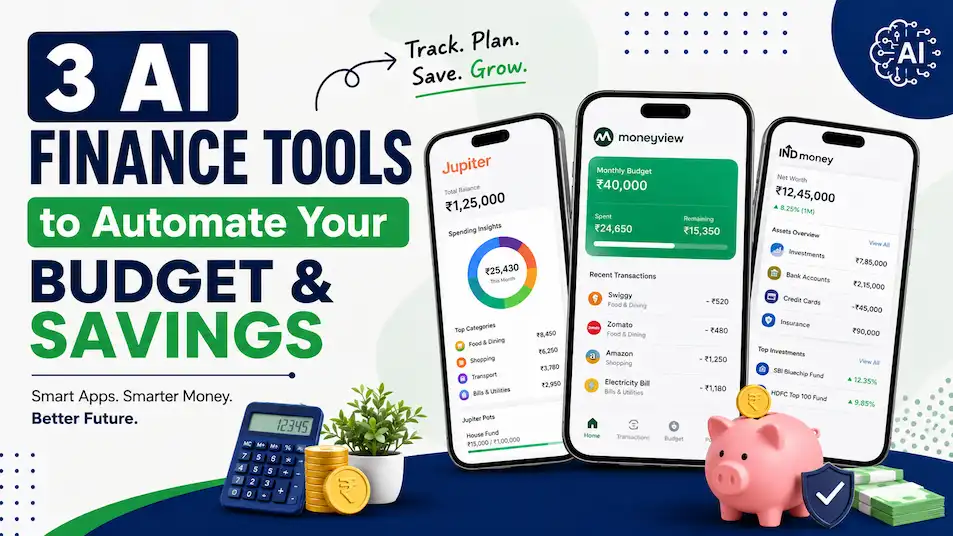
3 AI Finance Tools to Automate Your Budget and Savings
1. Jupiter Money
Jupiter Money is a personal finance app that combines money management with banking and spending features. It helps users track expenses, understand spending habits, and manage money through a single dashboard.
According to its official website, Jupiter offers Clear Categorisation, which automatically tags eligible payments into categories such as dining, travel, and shopping. It also supports linked accounts, allowing users to view supported external bank balances without switching between multiple apps.
Another useful feature is Jupiter Pots. You can set aside money for different spending needs and savings goals. Its Wellness Insights feature also analyses your financial habits and provides simple suggestions to help you manage money better.
For example, you can use Jupiter to understand how much you spend on shopping or food every month and decide how much money to set aside for future expenses.
Pros:
- Automatic categorisation of eligible payments
- Linked account tracking for a broader financial overview
- Jupiter Pots help organise money for different needs.
- Spending insights help identify unnecessary expenses.
Cons:
- Some features may require a Jupiter account or supported banking relationships.
- It offers several financial products, which may feel confusing to someone who only wants a basic expense tracker.
- Savings Pots are not the same as automatic investment returns or guaranteed savings.
Official source: Jupiter Money
2. Moneyview
Moneyview’s Money Manager reads your transaction-related SMS messages, after you give permission, and updates your reports automatically. This means no manual entry is required for many bank transactions.
It categorises spending, provides financial insights, and helps you set a monthly budget. It also offers bill reminders and shows spending trends over time, so you can spot where your money leaks.
According to Moneyview’s official FAQ, users can set a monthly budget, monitor their remaining balance, and review daily, weekly, monthly, or yearly spending summaries.
Pros:
- Very low effort to start
- Automatic transaction tracking through eligible SMS messages
- Bill reminders help you avoid late fees.
- Monthly budget tracking makes spending easier to monitor
Cons:
- It depends on SMS permissions, which some users may not want to give.
- Incorrect or missing transaction messages may affect tracking accuracy.
- Moneyview also offers lending products, so you may see loan-related offers inside the app. Borrow only if you truly need to.
Privacy note: Moneyview says it collects transactional SMS data with user permission and does not collect personal SMS messages. However, read its privacy policy carefully before granting access.
Sources:
3. INDmoney
INDmoney is a more comprehensive, all-in-one personal finance platform. It helps users track investments, expenses, financial goals, insurance-related information, bank accounts, and net worth in one place.
According to its official website, INDmoney allows users to track supported bank accounts, mutual funds, stocks, EPF, NPS, credit card bills, and other financial assets.
It also offers portfolio analytics to help users understand investment performance, returns, and financial risks. Its connected financial information can help users get a clearer picture of their overall financial position.
For example, instead of checking different apps to understand your investments and bank balances, you can use INDmoney to view supported financial information in one dashboard.
Pros:
- Good for seeing your overall financial picture
- Useful if you already invest in stocks or mutual funds
- Helps track supported external financial accounts
- Portfolio analytics and net worth tracking provide additional insights.
Cons:
- May feel crowded for a beginner who only wants a simple budget tracker
- Investment features are not the same as safe savings.
- Some features require linking external accounts and granting permissions.
Important: Tracking your investments does not mean the app automatically manages or protects your money. Market investments involve risks, and no returns are assured.
Sources:
Quick Comparison
| Table Header | Table Header | Table Header | Table Header |
|---|---|---|---|
|
Content |
Content |
Content |
Content |
This comparison is based on the apps’ publicly described features at the time of writing. Actual availability may depend on your account, permissions, and app version. Check each app’s current terms before relying on any feature.
How to Automate Your Budget and Savings with AI
Now let’s put this into practice.
- Pick one app. Using three apps at once only creates confusion. Start with the one that matches your needs.
- Connect your data. Grant SMS or account access only when you feel confident about the permissions being requested. Read the privacy policy first.
- Check the categories. Fix any wrong labels in the first week, so your spending reports become more accurate.
- Set a simple budget. A common rule of thumb is 50/30/20: 50% for needs, 30% for wants, and 20% for savings.
- Automate savings on salary day. Set up a standing instruction or an eligible automatic transfer that moves money to savings before you can spend it. Check the balance and transfer conditions first.
- Review once a week. Five minutes is enough to check your spending and see whether you are following your budget.
Example: How Much Can You Save Every Month?
Let’s understand this with a simple example.
If your monthly income is ₹40,000, the 50/30/20 rule gives you:
- Needs (50%): ₹20,000
- Wants (30%): ₹12,000
- Savings (20%): ₹8,000
Formula:
Monthly Income × 0.20 = Savings Target
If the app shows you spend ₹15,000 on wants, you know exactly where you need to cut back.
Remember, these figures are illustrative. Your perfect budget varies according to your earnings, financial obligations, and future aspirations.
Advantages and Disadvantages of AI Money Tools
Advantages
- Saves time on tracking expenses
- Makes overspending visible
- Helps build a saving habit through automation
- Provides a clearer picture of monthly spending
- Helps users make better budgeting decisions
Disadvantages
- May need access to sensitive financial data
- Automatic categories can sometimes be wrong.
- Some apps may promote loans or investment products.
- Features may differ between app versions and account types.
Common Mistakes to Avoid
- Giving app permissions without reading what they cover.
- Trusting automatic expense categories without a quick check.
- Setting a savings target that is too high and then quitting.
- Treating investing features as a replacement for an emergency fund.
- Using a tool for a week and never reviewing the reports.
Conclusion
AI finance tools won’t fix your money habits on their own, but they remove the boring part of tracking.
Jupiter Money suits you if you want spending insights and savings Pots, Moneyview if you want a simple expense tracker, and INDmoney if you want everything in one financial overview.
Begin with a single app, create a practical budget, and automate a modest amount of savings. You can raise it later.
Remember, the purpose of these tools is to make money management easier, not to make financial decisions blindly. Always review your transactions and keep control of your money.
Disclaimer: This article is for general information only and is not financial advice. App features, pricing, and privacy policies may change, so verify details before using any app.
FAQ's
Which AI finance tool is best for beginners in India?
Jupiter Money and Moneyview are useful starting points because they offer spending categorisation and expense tracking. Choose Jupiter if you want spending insights and savings Pots, or Moneyview if you prefer SMS-based expense tracking.
Are AI budgeting apps safe to use?
Safety depends on the app and the permissions you grant. Read what data it accesses, use a strong lock on your phone, and never share OTPs or banking passwords with any app.
Can AI really help me save money?
Yes, indirectly. These apps show where your money goes and can help you organise savings. However, your habits still decide the results. No tool can guarantee that you will save a fixed amount.
Are these AI expense tracking tools free?
Some core features may be available without a subscription, but pricing and premium plans can change. Check the app’s current terms before relying on any feature.
How much of my income should I save?
A common guideline is saving about 20% of your income, as in the 50/30/20 rule. Your ideal amount depends on your expenses, goals, and responsibilities, so adjust it realistically.
My name is Subodh Kumar, and I am a finance blogger at Financemantraa.com with a strong interest in personal finance, investing, and financial research spanning 4–5 years.
I enjoy researching financial topics and explaining complex money concepts in simple, easy-to-understand language. My areas of interest include stock market basics, IPOs, mutual funds, financial planning, insurance, saving strategies, and wealth building.
Through Financemantraa.com, I aim to help readers improve their financial knowledge, understand investment concepts, and make informed financial decisions. I focus on creating practical, beginner-friendly guides that make personal finance easier to understand and apply in everyday life.
I believe that financial education and smart money habits can help people work toward long-term financial stability. My goal is to make reliable, accessible, and informative financial content available to everyone.
Disclaimer: The information published on Financemantraa.com is for educational and informational purposes only. It should not be considered professional financial or investment advice.