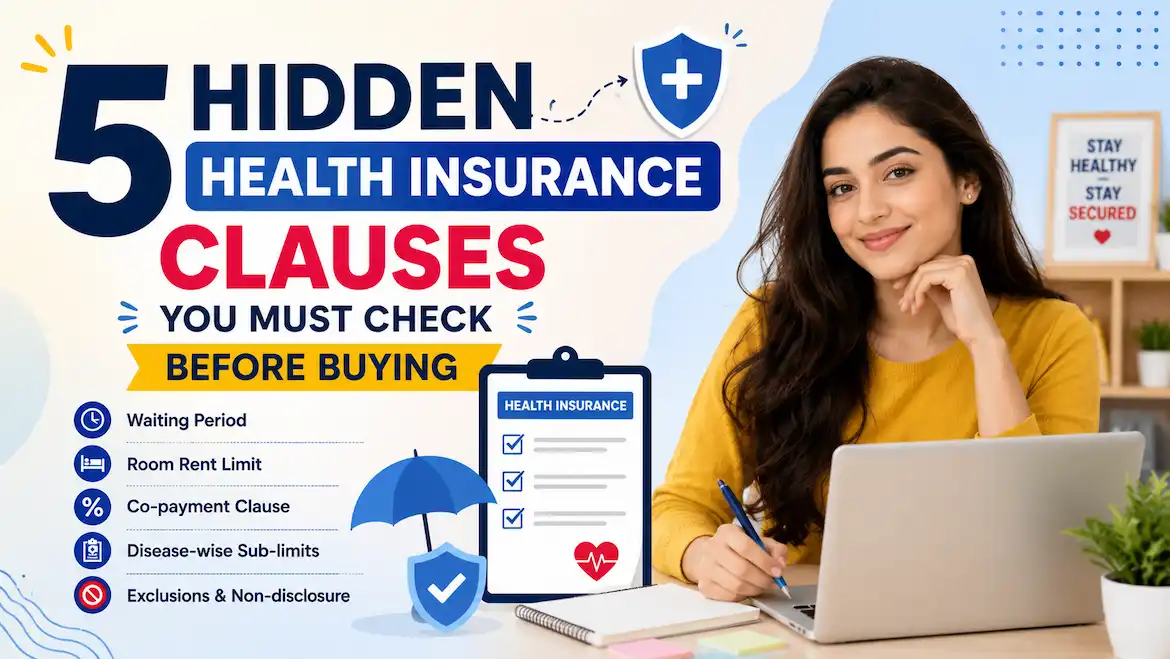
Many people buy a policy based on the premium and the sum insured. Then a claim comes, and the insurer pays less than they expected. Usually, the reason is not a trick. It is a clause sitting in the policy wording that nobody read.
In this guide, we will look at five health insurance clauses that can significantly affect your payout. By the end, you will know what to check before you buy so that you can avoid surprises at claim time.
In This Article
ToggleHighlight key
- Waiting periods decide when your cover actually starts.
- A room rent limit can affect more than just your room charges.
- Co-payment means you pay a fixed share of an approved claim.
- Disease-wise sub-limits cap what is paid for specific treatments.
- Exclusions and non-disclosure can lead to claim rejection or reduced payouts.
What Are Hidden Clauses in Health Insurance?
Hidden clauses are not secret. They are terms written in the policy document that people skip because the language is dense. They limit when, how much, or for what the insurer pays.
You will find them in the policy wording, the policy schedule, and the Customer Information Sheet (CIS). Let’s go through the five that matter most.
1. Health Insurance Waiting Period
The waiting period is the time following the purchase of a policy during which certain types of claims are not covered. Think of it like a probation period. You pay premiums, but some benefits are not active yet.
There are three common types:
- Initial waiting period: Often around 30 days, during which most illness-related claims are not covered. Accidental injuries are generally exempt, subject to policy terms.
- Specific illness waiting period: Applies to named conditions such as cataracts or hernia. Insurers may set this period at up to three years.
- Pre-existing disease waiting period: Applies to conditions you already have, such as diabetes or high blood pressure, subject to the policy’s definition of a pre-existing disease.
Under IRDAI’s Insurance Products Regulations, 2024, the waiting period for disclosed pre-existing diseases can be a maximum of 36 months of continuous coverage. Specific disease waiting periods can also be up to 36 months.
The moratorium period has been reduced to 60 continuous months (five years), including eligible portability and migration credits. After completing this period, an insurer generally cannot contest a policy or claim on grounds of non-disclosure or misrepresentation, except in cases of established fraud. If you increase your sum insured, the 60-month period applies separately to the enhanced portion.
Tip: Compare waiting periods across insurers. A policy with a one-year or two-year waiting period for pre-existing diseases may suit you better than one with the full three years. Also, if you switch insurers later, the waiting period credit you have already earned can be transferred through portability, subject to applicable rules.
Sources:
2. Room Rent Limit in Health Insurance
Some policies cap the room rent they will pay per day. It may be a fixed rupee amount or a percentage of the sum insured. The catch is what happens if you choose a costlier room.
The insurer may apply a proportionate deduction if the policy includes such a clause. This means certain room-linked medical expenses may also be reduced in proportion to the difference between your eligible room rent and the room you choose.
Under applicable IRDAI requirements, insurers must clearly explain the associated expenses covered by a proportionate deduction in their policy terms. The exact treatment of expenses depends on the policy wording and applicable regulatory provisions.
Example (illustrative):
- Your room limit is ₹5,000 per day.
- You take a room costing ₹10,000 per day.
- Your room costs twice the eligible limit.
- If the policy applies a 50% proportionate deduction to eligible room-linked expenses, only 50% of those expenses may be payable.
If eligible associated medical charges were ₹60,000, you may have to bear around ₹30,000 of those charges, in addition to the room rent difference.
This is only an illustrative calculation. The actual deduction depends on the policy wording, hospital billing practices, and applicable terms. It does not mean that 50% of the entire hospital bill will automatically be deducted.
Tip: Some health insurance products offer no room rent limit. They may cost a little more, but they can help avoid room-category-related proportionate deductions. Compare the complete coverage and not just the premium.
Source:
3. Co-payment Clause in Health Insurance
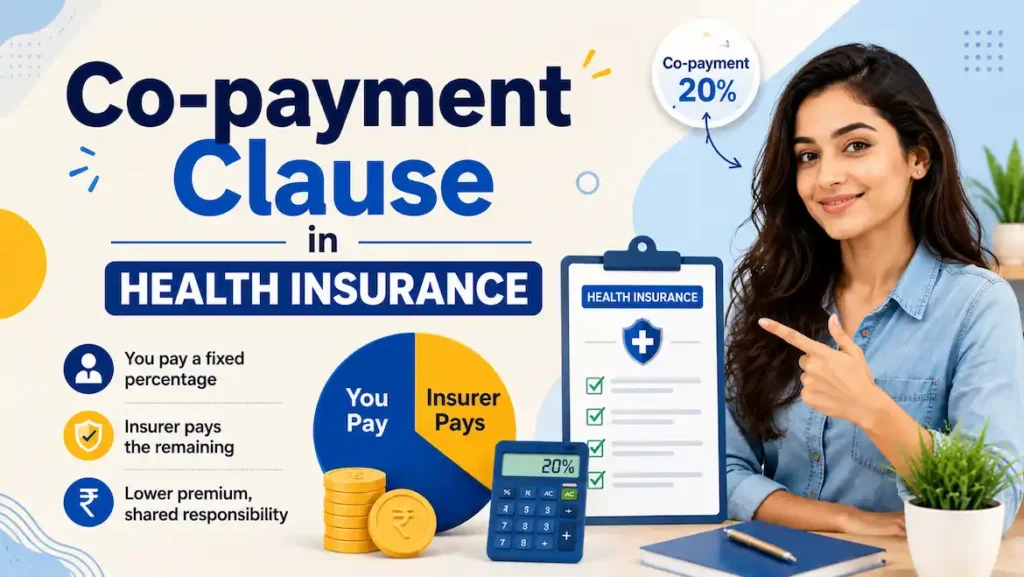
Co-payment is the percentage of an approved claim that you pay yourself. The insurer pays the remaining amount, subject to the policy terms. It may be voluntary, where you accept it to lower your premium, or mandatory, where it is built into the policy. Some senior citizen plans include it.
Example: With a 20% co-payment and an approved claim of ₹3,00,000, the insurer pays ₹2,40,000 and you pay ₹60,000.
Advantages:
- Lower premium in some policies.
- You may get an affordable policy by sharing a portion of claim expenses.
Disadvantages:
- You pay a percentage of every applicable claim.
- Your out-of-pocket expenses increase as the approved claim amount grows.
Tip: If you choose co-payment, make sure you can comfortably afford your share during a major hospitalisation. Also, check whether the co-payment applies to all claims or only specific treatments, hospitals, or age groups.
4. Disease-wise Sub-limits
A sub-limit is a cap on what the insurer will pay for a particular illness or procedure, even if your total sum insured is much higher. Examples may include a fixed limit for cataract surgery or certain other treatments.
Example (illustrative): Your policy has a ₹30,000 sub-limit for cataract surgery. The bill is ₹60,000. Even with a ₹10 lakh sum insured, the insurer will pay only up to ₹30,000 under this sub-limit, subject to other applicable policy conditions. You may have to pay the remaining amount.
Sub-limits and co-payment can also work together. A room rent clause may reduce eligible room-linked expenses, a disease-wise sub-limit may cap payment for a particular procedure, and co-payment may require you to pay a percentage of the approved claim.
Tip: Read the policy schedule and wording carefully to find all sub-limits. Prefer plans with fewer restrictions or no disease-wise sub-limits, if they fit your budget and healthcare needs.
5. Health Insurance Exclusions and Non-disclosure
Exclusions are expenses, treatments, or medical conditions that a policy does not cover. Common examples may include certain cosmetic procedures, non-medical items, and some dental or fertility treatments, although coverage varies by insurer and policy.
Always check the permanent exclusions section and understand whether any treatment is covered under specific conditions or add-ons.
Non-disclosure is another major risk. If you hide a health condition or provide incorrect medical information when buying a policy, the insurer may investigate the matter and reject or reduce a claim where permitted under the policy and applicable regulations.
Claims may be rejected, partially paid, or delayed because of exclusions, waiting periods, applicable limits, co-payment, material non-disclosure, or incomplete claim documents.
Tip: Be honest on the proposal form. Disclose your medical history, previous treatments, existing conditions, and prescribed medicines accurately. It can help prevent disputes during claim settlement.
Source:
Quick Checklist Before You Buy
- Check the pre-existing disease and specific illness waiting periods.
- Look for “room rent,” “proportionate deduction,” and “sub-limit” in the policy wording.
- Check for any co-payment, whether voluntary or mandatory.
- Read the exclusions list fully.
- Confirm your preferred hospitals are in the cashless network.
- Declare all medical history honestly.
Common Mistakes to Avoid
- Choosing a policy only because the premium is lowest.
- Reading the brochure but not the policy wording.
- Skipping the Customer Information Sheet.
- Choosing a higher room category at the hospital without checking your policy limit.
- Ignoring co-payment and disease-wise sub-limits.
- Not disclosing existing medical conditions when applying.
Conclusion
Health insurance clauses decide how much help you really get when you need it. A big sum insured looks good on paper, but waiting periods, room rent limits, co-payment, sub-limits, and exclusions shape the real payout.
Take some time to read these five clauses before you buy. Compare two or three policies side by side, and ask the insurer to explain anything unclear. A little research today can help you avoid unexpected expenses during a medical emergency.
Disclaimer: This article is for general education only and is not financial or insurance advice. Rules, policy terms, and premiums can change and differ between insurers. Check your policy wording and current IRDAI guidance before deciding.
FAQ's
What are hidden clauses in health insurance?
They are policy terms that limit your payout, such as waiting periods, room rent limits, co-payment, sub-limits, and exclusions. They are written in the policy wording but often go unread before purchase.
What should I check before buying health insurance?
Check waiting periods, room rent limits, co-payment, sub-limits, exclusions, and the cashless hospital network. Also compare claim process details and be honest about your medical history on the proposal form.
Can health insurance companies reject claims?
Yes. Claims can be rejected or reduced for reasons such as applicable waiting periods, exclusions, material non-disclosure, or policy conditions. Reading your policy carefully and declaring everything honestly can help lower this risk.
What is the waiting period in health insurance?
It is the time after purchase when certain claims are not payable. Under IRDAI rules, the waiting period for disclosed pre-existing diseases can be up to 36 months of continuous coverage. Many insurers may offer shorter waiting periods.
How can I avoid health insurance claim rejection in India?
Disclose your health history fully, understand exclusions and waiting periods, and keep premiums paid on time. Use network hospitals for cashless care where suitable, follow the insurer’s claim procedure, and keep all bills and medical reports ready for submission.
My name is Subodh Kumar, and I am a finance blogger at Financemantraa.com with a strong interest in personal finance, investing, and financial research spanning 4–5 years.
I enjoy researching financial topics and explaining complex money concepts in simple, easy-to-understand language. My areas of interest include stock market basics, IPOs, mutual funds, financial planning, insurance, saving strategies, and wealth building.
Through Financemantraa.com, I aim to help readers improve their financial knowledge, understand investment concepts, and make informed financial decisions. I focus on creating practical, beginner-friendly guides that make personal finance easier to understand and apply in everyday life.
I believe that financial education and smart money habits can help people work toward long-term financial stability. My goal is to make reliable, accessible, and informative financial content available to everyone.
Disclaimer: The information published on Financemantraa.com is for educational and informational purposes only. It should not be considered professional financial or investment advice.