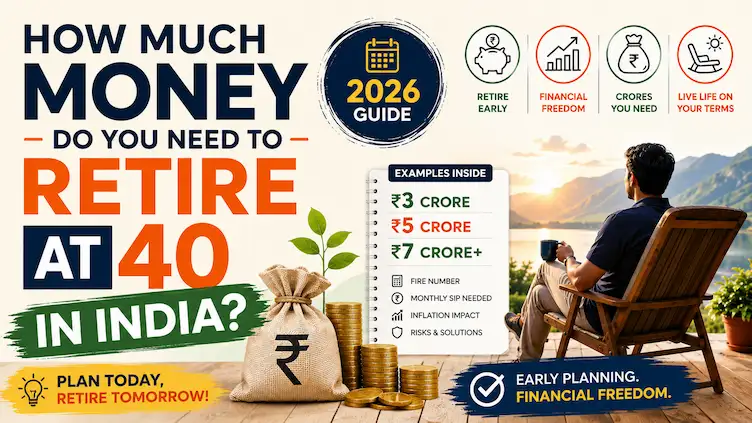
Imagine quitting your job at 40 and living on your investments. It sounds exciting, but the big question is how much money do you need to retire at 40 in India. The right answer depends on your monthly expenses, inflation, and how long you plan to get by using your savings.
In this guide, we will learn how to calculate your FIRE number, check examples for ₹3 crore and ₹5 crore, estimate the monthly SIP you may need, and look at the risks.
In This Article
ToggleHighlight key
- Your retirement corpus depends mainly on your expenses, not your age.
- A simple rule: Yearly expenses at retirement × 25 to 33.
- Inflation is one of the biggest challenges in early retirement planning in India.
- A ₹3 crore corpus may support an initial withdrawal of about ₹87,500 per month at a 3.5% withdrawal rate, before taxes.
- All return and inflation figures here are assumptions, not guarantees.
What Does Retiring at 40 Really Mean?
Retiring at 40 usually means financial independence. Your investments pay for your living costs, so work becomes optional. This idea is popular as the FIRE movement (Financial Independence, Retire Early).
In India, FIRE needs extra care because your money may have to last 45 years or more.
How to Calculate Your FIRE Number in India
Your FIRE number is the total corpus you need to stop working. Let’s break it into three steps.
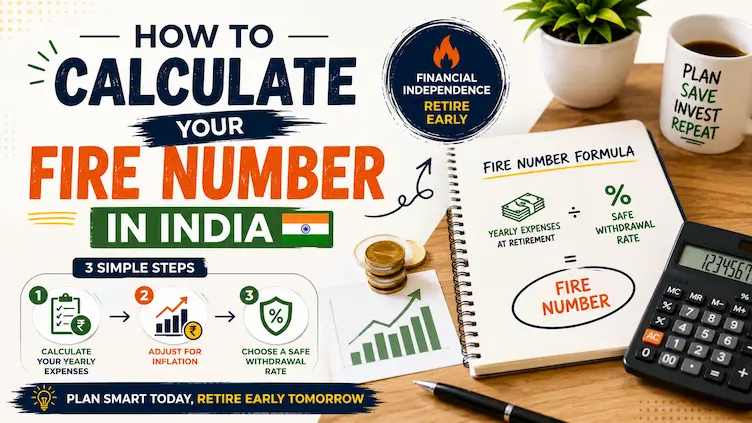
Step 1: Find Your Yearly Expenses
Add up rent, food, EMIs, school fees, insurance, travel, and medical costs. Multiply the monthly total by 12.
Also, include irregular expenses such as home repairs, vehicle maintenance, family functions, and unexpected medical bills. This will help you avoid underestimating your retirement needs.
Step 2: Adjust for Inflation
Prices rise every year. India’s retail inflation was 6.09% in October 2026 (provisional), according to the Ministry of Statistics and Programme Implementation (MoSPI).
The RBI’s inflation target for April 2026 to March 2031 is 4%, with a tolerance band of 2% to 6%. A single month’s inflation figure above 6% does not automatically mean that the RBI has failed to meet its target.
For our retirement calculations, we will use 6% annual inflation as a planning assumption, not a forecast. Your actual living costs may increase at a different rate.
Sources:
Step 3: Choose a Withdrawal Rate
The withdrawal rate is the portion of your retirement corpus that you withdraw each year.
The popular 4% rule (corpus = 25 × yearly expenses) comes from US retirement research. However, its results may not directly apply to India because market returns, inflation, taxes, and investment conditions are different.
A PFRDA-published study, Balancing Acts: Safe Withdrawal Rates in the Indian Context, discusses a 3% to 3.5% withdrawal rate as a more suitable range in its historical analysis for India. There is no guarantee that your money will last throughout your entire retirement. For a retirement lasting 45 years or more, you should carefully consider a conservative withdrawal rate and review your portfolio regularly.
Formula:
FIRE Number = Yearly Expenses at Retirement ÷ Withdrawal Rate
For example, if your annual expenses at retirement are ₹10.7 lakh and you choose a 3.5% withdrawal rate:
₹10.7 lakh ÷ 0.035 = Approximately ₹3.06 crore.
Source: PFRDA – Pension Security in India: Balancing Acts: Safe Withdrawal Rates in the Indian Context
Retirement Corpus at Age 40: Real Examples
Let’s assume you are 30 today, will retire in 10 years, expect 6% annual inflation, and use a 3.5% initial withdrawal rate.
| Monthly Expenses Today | Estimated Monthly Expenses at 40 | Early Retirement Corpus Needed at 40 |
|---|---|---|
|
₹30,000 |
₹53,700 |
About ₹1.84 crore |
|
₹50,000 |
₹89,500 |
About ₹3.07 crore |
|
₹75,000 |
₹1.34 lakh |
About ₹4.60 crore |
|
₹1,00,000 |
₹1.79 lakh |
About ₹6.14 crore |
Here is the math for ₹50,000.
Yearly expenses today are ₹6 lakh. After 10 years at 6% annual inflation, they become about ₹10.75 lakh.
Now divide ₹10.75 lakh by 0.035, and you get roughly ₹3.07 crore.
If you use the 4% rule instead, the same person needs about ₹2.69 crore. At 3%, it rises to about ₹3.58 crore. A small change in the withdrawal rate changes the corpus significantly.
These are illustrative estimates. They do not include a separate emergency reserve or any additional buffer for unexpected expenses.
Can You Retire at 40 with ₹3 Crore or ₹5 Crore in India?
Can I retire at 40 with ₹3 crore in India?
At a 3.5% initial withdrawal rate, ₹3 crore gives about ₹10.5 lakh a year, or ₹87,500 a month before taxes. This may work for a single person or a couple with low costs, no big loans, and adequate health insurance. It may be tight for a family in a metro city.
Can I retire at 40 with ₹5 crore in India?
₹5 crore gives about ₹17.5 lakh a year, or roughly ₹1.46 lakh a month before taxes. That is more comfortable, but you must still plan for inflation, medical costs, and children’s education.
Remember that these amounts are in the rupees of the year you retire. Prices will keep rising afterwards, so your withdrawals may need to increase over time. Your portfolio must also generate enough returns to support future withdrawals.
Monthly SIP Required to Retire at 40 in India
A SIP (Systematic Investment Plan) lets you invest a fixed amount every month in mutual funds.
Let’s say you start at 30 with no savings and want about ₹3 crore by 40.
If your investments grow at an assumed 12% annualised return, you would need roughly ₹1.30 lakh per month for 10 years. At an assumed 10% annualised return, it rises to about ₹1.47 lakh per month.
These are approximate calculations based on monthly investments and monthly compounding. Market returns are never guaranteed, and actual results can be much lower or higher.
Starting earlier, saving a larger share of income, or increasing your SIP every year can reduce the burden. This is why early retirement at 40 is realistic mainly for people with high savings rates.
Best Investment Plan for Early Retirement in India
There is no single best plan, and we cannot promise returns. Most early retirement portfolios mix a few asset types:
- Equity (mutual funds, index funds): For long-term growth that may help beat inflation, but with high short-term ups and downs.
- Debt (FDs, debt funds, bonds): For stability and to cover a few years of expenses.
- Gold: A small allocation for diversification.
- Emergency fund and health insurance: Essential before you quit work.
Also check the lock-in and withdrawal rules of PPF, EPF, and NPS. Access to these investments may be restricted by specific withdrawal, maturity, or exit conditions. Do not assume that all your retirement savings will be immediately available when you turn 40. Confirm the latest rules on official websites.
Tax matters too. Under Section 112A, eligible long-term capital gains from listed equity shares, equity-oriented mutual funds, and business trusts are generally taxed at 12.5% on aggregate annual gains exceeding ₹1.25 lakh, subject to applicable STT and other conditions. Other investments and short-term gains may follow different tax rules.
Your actual withdrawals may have tax implications, so keep a suitable buffer and plan your investments tax-efficiently.
Source: Income Tax Department – Tax on Sale of Shares in India
Advantages and Disadvantages of Retiring at 40
Advantages
- Freedom to choose how you spend your time.
- More time for family, health, and hobbies.
- Less work stress.
- Opportunity to explore a passion or start a small business.
Disadvantages
- You need a very large corpus for a long retirement.
- Inflation and market crashes can hurt more over 45+ years.
- Health costs may rise as you age.
- You lose a regular salary, employer benefits, and future salary growth.
How to Protect Your Retirement Corpus from Unexpected Expenses
Retiring at 40 means you may depend on your investments for several decades. Therefore, building a large corpus is only one part of the plan.
Here are a few things to consider:
- Keep an emergency fund: Maintain enough liquid savings for unexpected expenses and temporary income gaps.
- Buy adequate health insurance: Medical expenses can increase significantly over a long retirement period.
- Diversify your investments: Avoid depending entirely on equity or fixed deposits.
- Plan for market crashes: A market fall during the first few years of retirement can affect how long your money lasts. This is known as sequence-of-returns risk.
- Review your withdrawal rate: Check your expenses, portfolio performance, and inflation every year.
- Keep a tax buffer: Your actual investment income and withdrawals may have tax implications.
A flexible retirement plan can help you reduce spending temporarily during difficult market conditions instead of selling investments at unfavourable prices.
Common Mistakes to Avoid
Ignoring inflation: ₹50,000 today will not buy the same things in 10 years.
Assuming high returns every year: Markets can fall for years, so do not build your retirement plan around guaranteed high returns.
Forgetting health insurance: One hospital bill can disturb your plan.
Having no emergency fund: You may be forced to sell investments at a bad time.
Not planning for taxes: Taxes can reduce your actual investment income and withdrawals.
Keeping EMIs: Try to clear major home and car loans before retiring.
Underestimating retirement duration: Retiring at 40 could mean funding 45 to 50 years or more of living expenses.
Conclusion
So, how much money do you need to retire at 40 in India? For many people, the answer may fall between ₹3 crore and ₹6 crore or more, depending on their lifestyle and expenses. The exact number depends on inflation, investment returns, taxes, and the withdrawal rate.
Calculate your own FIRE number, build your SIP habit early, and review your plan every year. Retiring early is possible, but it needs patience, disciplined investing, and honest planning.
Disclaimer: This article is for educational purposes only and is not personalised financial advice. Investment returns are not guaranteed, and tax rules and rates may change. Please consult a SEBI-registered investment advisor before making financial decisions.
FAQ's
How many crores do you need to retire at 40 in India?
It depends on your expenses. For ₹50,000 monthly spending today, a 30-year-old may need roughly ₹3.07 crore by age 40, using 6% annual inflation and a 3.5% initial withdrawal rate. Higher expenses need a larger corpus.
Is ₹5 crore enough to retire at 40 in India?
It can be enough for a moderate lifestyle. At a 3.5% initial withdrawal rate, ₹5 crore gives about ₹1.46 lakh per month before taxes. It may fall short if you have a big family, loans, or high medical costs.
What is the FIRE number in India?
Your FIRE number is the corpus you need to live on your investments without depending on a regular job. Divide your yearly expenses at retirement by your chosen withdrawal rate. A 3% to 3.5% withdrawal rate can be used as a conservative planning assumption, but it does not guarantee that your money will last forever.
How much SIP do you need to retire at 40 in India?
To build about ₹3 crore in 10 years at an assumed 12% annualised return, you would need a SIP of roughly ₹1.30 lakh per month. Returns are not guaranteed, so actual results can differ.
Is it realistic to retire at 40 in India?
It is possible but difficult. You need a high savings rate, steady income for many years, and disciplined investing. Rising prices and healthcare costs make early retirement planning more demanding in India.
My name is Subodh Kumar, and I am a finance blogger at Financemantraa.com with a strong interest in personal finance, investing, and financial research spanning 4–5 years.
I enjoy researching financial topics and explaining complex money concepts in simple, easy-to-understand language. My areas of interest include stock market basics, IPOs, mutual funds, financial planning, insurance, saving strategies, and wealth building.
Through Financemantraa.com, I aim to help readers improve their financial knowledge, understand investment concepts, and make informed financial decisions. I focus on creating practical, beginner-friendly guides that make personal finance easier to understand and apply in everyday life.
I believe that financial education and smart money habits can help people work toward long-term financial stability. My goal is to make reliable, accessible, and informative financial content available to everyone.
Disclaimer: The information published on Financemantraa.com is for educational and informational purposes only. It should not be considered professional financial or investment advice.