Have you ever come across the name PB Fintech while reading about the stock market and wondered what the company actually does and whether its shares are worth understanding? You’re not alone. PB Fintech has attracted attention because of its growing presence in India’s online insurance and financial services space.
When I first started looking into the company, I realized that simply checking the PB Fintech share price doesn’t tell the complete story. To understand a stock properly, it is important to look beyond the price and explore the company’s business model, revenue, profits, growth strategy, and potential risks.
In this article, we’ll take a simple and practical look at PB Fintech’s business, financial performance, share price factors, growth opportunities, and key risks. The goal is to make the topic easy to understand, even if you’re new to stock market investing.
So, grab a cup of tea and let’s explore the PB Fintech stock story step by step.
Highlight key
- Current share price: around ₹1,399 (as of September 24, 2026)
- Market cap: about ₹64,721 crore
- 52-week high/low: ₹1,964 / ₹1,334
- Stock P/E ratio: around 86.5
- Book value: around ₹158 per share
- Dividend: the company does not pay any dividend right now
- Parent brands: Policybazaar and Paisabazaar
What Is PB Fintech and What Does It Do?
PB Fintech is the parent company behind two very popular Indian platforms, Policybazaar and Paisabazaar. If you have ever compared health insurance or term insurance plans online in India, there is a good chance you landed on Policybazaar without even realizing it belongs to PB Fintech.
The company started way back in 2008, and honestly, its journey has been quite interesting. It began as a small comparison website and slowly grew into India’s largest online insurance marketplace. Policybazaar alone holds a huge share of the online insurance distribution space in India, and that is not a small achievement in such a competitive market.
Paisabazaar, the other big brand under the group, helps people compare and apply for loans and credit cards. So in short, this company sits right at the center of how many Indians research and buy insurance and credit products today. This business model is asset-light in nature, which means it does not need heavy machinery or factories, it mainly runs on technology, trust, and partnerships with insurers and lenders.
What I personally like about this setup is how simple the idea sounds, yet how hard it is to execute well. Building trust online, in a country where insurance was traditionally sold face-to-face by an agent, is not an easy task. The platform had to convince lakhs of Indians that comparing and buying a policy online is safe and reliable, and it managed to do that at a scale very few competitors have matched.
PB Fintech Share Price Today: What Is Happening?
Tell me the truth, have you checked the PB Fintech share price chart recently? It has been quite a rollercoaster. The stock touched a 52-week high of around ₹1,964 and also slipped to a low near ₹1,334 in the same period. As of the latest trading session, PB Fintech share price is hovering around ₹1,399, and the stock has shown noticeable volatility.
This kind of movement is common with new-age tech and internet companies. In my experience, such stocks react very quickly to quarterly results, management commentary, and even rumours. In fact, there was recent market chatter around leadership changes at the top, which the management officially denied. This shows how sensitive investor sentiment can be for a stock like this one.
If you think as I do, short-term price swings should not scare you away immediately. Instead, focus on the actual business performance, which we will discuss next. Now let’s also understand something important here: the share price of any internet or fintech company usually depends heavily on how the market values future growth, not just the current year’s numbers. That is exactly why even a small miss in quarterly guidance can push the price down sharply, and a strong quarter can push it up just as fast.
PB Fintech Business Model Explained
This is where the company’s business model starts to become truly intriguing. The company earns money mainly through commissions it receives from insurance companies and lenders whenever a customer buys a policy or takes a loan through its platform. It is a marketplace model, much like how e-commerce sites earn a cut on every sale.
Beyond Policybazaar and Paisabazaar, the group has also expanded into newer areas like PB Partners, which supports offline insurance advisors, and PB Pay, which recently received approval to operate as a payment aggregator. This shows that management is not sitting quietly; it keeps trying to widen its business.
Honestly, this diversification is a good sign. Relying on just one product line is risky in any business, and the leadership team seems to understand that lesson well. There is also a growing focus on renewal business, meaning customers who already bought a policy through the platform tend to renew it there too, and renewals usually come with better margins than fresh sales. Over time, as more customers stay on the platform for years, this renewal income can become a steady and predictable revenue stream.
PB Fintech Financial Results and Revenue Growth
Now let’s talk numbers, because that is what really matters for any stock analysis. The company’s revenue has grown at an impressive pace over the last few years.
- FY2022 revenue: around ₹1,425 crore
- FY2023 revenue: around ₹2,558 crore
- FY2024 revenue: around ₹3,438 crore
- FY2025 revenue: around ₹4,977 crore
- FY2026 revenue: around ₹6,794 crore
That is a huge jump, friends. In fact, the compounded sales growth over the last three years stands close to 38 percent, which is genuinely strong for a company of this size. To put this in perspective, very few listed Indian companies manage to grow revenue at this pace for so many consecutive years, and that alone explains why so many investors keep a close watch on this stock. Now let’s talk about whether this growing revenue is actually translating into profit, because revenue growth alone does not always mean a healthy company.
PB Fintech Profit and Loss Analysis
This is the part where the story gets really encouraging. For a long time, the company was posting heavy losses, which is fairly normal for internet businesses in their early growth phase. However, things changed from FY2024 onwards.
- FY2022 net loss: around ₹833 crore
- FY2023 net loss: around ₹488 crore
- FY2024 net profit: around ₹64 crore
- FY2025 net profit: around ₹352 crore
- FY2026 net profit: around ₹670 crore
In my experience tracking such turnaround stories, this kind of consistent profit growth after years of losses is exactly what long-term investors look for. The company’s profit growth over the last five years has compounded at a strong rate, and the trend of the recent quarters also looks encouraging, with operating margins slowly improving.
However, do not ignore that the stock’s P/E ratio of around 86.5 is quite high. This basically means investors are paying a premium price today, expecting much bigger profits in the future. If that growth does not show up, the stock could see pressure. It is also worth noting that a portion of the reported profit comes from other income, such as interest earned on the company’s cash reserves, and not purely from its core insurance and lending business. A genuine investor should always look beyond the headline profit number and check where that profit is actually coming from.
PB Fintech Shareholding Pattern
Let’s talk about who actually owns the shares. Over the recent quarters, foreign institutional investors, or FIIs, have gradually reduced their holdings, moving from around 49 percent to close to 37 percent. On the other side, domestic institutional investors, or DIIs, have been steadily increasing their stake, now holding around 40 percent.
This shift is worth noticing. It usually means Indian mutual funds and insurance companies are showing more confidence in this business, even as some foreign investors book profits. Public shareholding, meaning retail investors like you and me, has come down a bit as institutions take a bigger seat at the table. In my experience, a rising DII stake often signals that domestic fund managers, who track companies very closely, see long-term value here, even if the near-term price feels expensive.
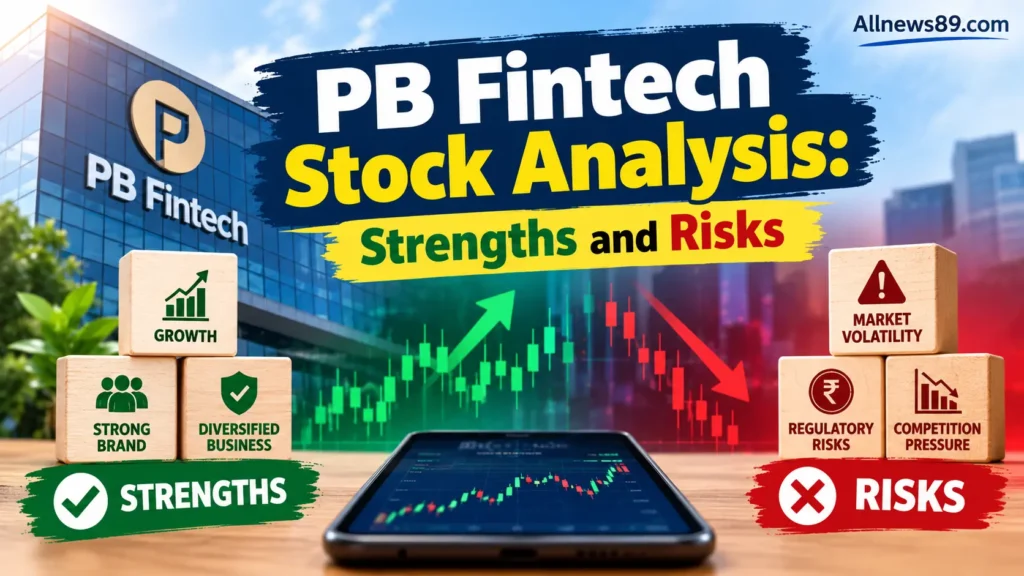
PB Fintech Stock Analysis: Strengths and Risks
Now, let’s be genuine here, because I promised you honest information, not hype.
The good side:
- The company is almost debt-free, which is a healthy sign.
- Strong revenue growth, with sales growing much faster than the broader industry
- The company has finally turned profitable, and profit growth has been strong.
- Working capital days have improved a lot, showing better cash management.
The concerning side:
- The stock trades at a high valuation, nearly 9 times its book value.
- Return on equity has been low historically, though it is improving.
- The company does not pay any dividend, so there is no passive income for shareholders right now.
- A good chunk of profit comes from other income, not just the core business.
If something is good, I will say it is good, and if something is a concern, I will not hide it either. That is the only fair way to look at any stock.
Is PB Fintech a Good Stock to Invest In?
This is probably the question that brought you here. Friends, I cannot tell you exactly what to do with your money, and honestly, nobody genuinely can. But here is how I look at it.
This company has clearly moved from a loss-making internet business to a profitable, cash-generating one, and that transition is not easy to achieve. The core business of insurance and lending distribution in India still has a long runway, since a large part of the country remains underinsured.
At the same time, the current share price already reflects high expectations. If you are someone who believes in India’s growing digital insurance story and can handle short-term price swings, PB Fintech might fit into a long-term portfolio. But if you are looking for stable dividends or a low-risk investment, this stock may not be for you right now.
I remember telling my uncle exactly this back then, that this is not a stock for someone who checks their portfolio every single day and panics on red days. It is more suited to someone who can hold on for several years and let the underlying business growth play out. He eventually decided to invest a small amount, purely as a long-term bet, and treated it as one part of a diversified portfolio rather than his only investment. That, in my opinion, is the smarter way to approach a growth stock like this.
PB Fintech Future Growth Prospects
Looking ahead, this company’s growth will likely depend on how well it expands products like PB Partners and PB Pay, alongside its core insurance and lending marketplaces. India’s insurance penetration is still quite low compared to many other countries, and that gap itself is a big opportunity.
Therefore, if the company continues improving its operating margins while growing revenue, the profit numbers could keep climbing in the coming years. However, competition from other insurtech players and banks entering the digital space is something investors should keep an eye on. Regulatory changes in the insurance and lending sectors could also affect commission rates, and that is another factor worth tracking every year when new results come out.
Final Thoughts
The PB Fintech journey from heavy losses to steady profits is genuinely one of the more interesting turnaround stories in the Indian stock market. Its share price will keep moving with market moods, quarterly results, and industry news; that is simply how the stock market works.
If you plan to invest in this company, do your own research, look at the numbers we discussed here, and think about your own risk appetite. I am not a financial advisor, and this article is meant to inform you, not to push you toward any decision. Always talk to a certified financial advisor before putting real money into any stock, including PB Fintech.
Disclaimer:
This article is for informational purposes only and should not be considered investment advice. Stock market investments carry risk, and past performance does not guarantee future returns. Please consult a certified financial advisor before making any investment decisions.
FAQ's
What is the current PB Fintech share price?
As of late September 2026, PB Fintech share price is trading around ₹1,399 on NSE and BSE, though the exact price keeps changing during market hours as trading continues.
Is PB Fintech a profitable company now?
Yes, PB Fintech turned profitable from FY2024 onwards, and its net profit has grown each year steadily since then, reaching around ₹670 crore in FY2026, per its consolidated results.
What is PB Fintech’s business model?
PB Fintech earns commissions by helping users compare and buy insurance and loan products through Policybazaar and Paisabazaar, working as a digital marketplace connecting customers with insurers and lenders.
Does PB Fintech pay dividends to shareholders?
No, PB Fintech currently does not pay any dividends to its shareholders, as the company prefers reinvesting profits into growing its insurance and lending businesses further.
Is PB Fintech stock overvalued right now?
PB Fintech trades at a high P/E ratio near 86.5 and nearly 9 times its book value, so many analysts consider the stock richly valued compared to its historical earnings.
Who are the major investors in PB Fintech?
PB Fintech’s shareholding includes foreign institutional investors around 37 percent, domestic institutional investors near 40 percent, and the remaining held by public and other shareholders.