Friends, if you are exploring mid-cap mutual funds these days, you must have come across the Nippon India Growth Mid Cap Fund. I remember when a close friend of mine first asked me about it last year. He had some extra money and wanted it to grow faster than a fixed deposit. That’s when we sat down together and dug into its NAV, returns, and risk level. In this guide, I will share everything we found, in simple words, so you don’t have to run from website to website like we did.
This fund has been around for a long time and has a strong track record in the mid-cap space. But tell me the truth, does that mean it is right for you too? Let’s find out, step by step.
Highlight key
- Category: Mid Cap Mutual Fund
- Launched: October 1995
- Fund Manager: Rupesh Patel (since January 2023)
- Risk Level: Very High (as per SEBI riskometer)
- Minimum SIP: Just ₹100 per month
- Benchmark: Nifty Midcap 150 TRI
- Rating: 5 Star (as per recent ratings)
What is This Mid Cap Fund?
Nippon India Growth Mid Cap Fund is an equity scheme that mainly puts money into mid-sized companies, bigger than small caps but not yet large-cap giants. The idea is simple. Mid-cap companies often grow faster than large caps, so there is a good chance of higher returns over time.
It was launched way back in 1995, so it has already seen many market ups and downs. This long history gives it a kind of experience that newer funds don’t have. In my experience, funds that have survived several market cycles tend to handle bad phases a little better, because the fund house has already learned hard lessons.
The scheme is managed by Rupesh Patel, at the helm since January 2023. He decides which mid-cap stocks to buy, hold, or sell, based on research and market conditions. So when you invest here, you are trusting his team’s judgement with your money.
Nippon India Growth Mid Cap Fund NAV Today
NAV, or Net Asset Value, is simply the price of one unit. As of September 2026, the Direct Growth plan NAV is close to ₹4,950, while the Regular Growth plan is a bit lower, around ₹4,500. These figures change every working day depending on market movements.
Don’t get confused by a high NAV number. It does not necessarily indicate that the fund is overpriced or that investors should expect lower returns. It just means the scheme has been around for a long time and has grown steadily. What actually matters is the percentage growth of your investment, not the raw NAV figure.
You can check the latest NAV directly on the Nippon India Mutual Fund website, or on platforms like Value Research, Groww, or Zerodha Coin. I personally check it once a week, not daily, because checking every day just creates unnecessary stress.
Nippon India Growth Mid Cap Fund Returns
Now let’s talk about the part everyone cares about, the returns. This fund has a solid history of beating its own benchmark, the Nifty Midcap 150 TRI, across most time periods.
Here is a rough picture:
- 1 Year Return: around 9%
- 3 Year Return: around 20.8% (annualised)
- 5 Year Return: around 20.3% (annualised)
- Since Inception: strong long-term growth since 1995
These historical returns look attractive, but please remember one thing, friends. Past performance never guarantees future results. The market can be kind one year and harsh the next. If you think as I do, treat these numbers as a guide, not a promise.
The fund has stayed ahead of many peers in its category over three-, five, and even ten-year periods, according to recent rankings. That said, mid-cap funds as a whole go through rough patches too, so don’t expect a smooth straight line upward.
SIP Investment Made Simple
SIP, or Systematic Investment Plan, is honestly the easiest and most stress-free way to invest here. Instead of putting a big lump sum at once, you invest a fixed small amount every month.
The SIP option starts at just ₹100 per month, making it easy for almost anyone to begin. You don’t need to time the market or wait for the “perfect” day. Your money automatically buys more units when the price is low and fewer when the price is high. Over time, this helps balance out the overall average cost of your investment.
Say you had started a monthly SIP of ₹10,000 about ten years back. Based on past data, that kind of disciplined investing could have grown to a much larger amount than what you actually put in, thanks to compounding and rupee cost averaging. This is exactly why patient SIP investors often do better than people who try to time entry and exit.
If you are new to this, a SIP calculator, available on most fund and broker websites, can help you estimate future value based on your monthly amount and expected return rate.
Direct Growth vs Regular Plan
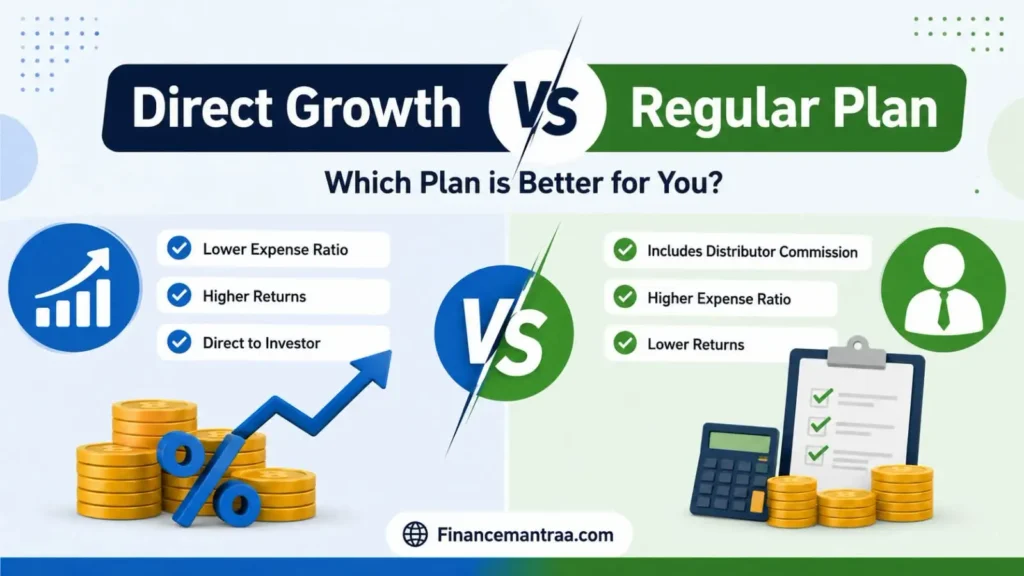
Now here comes an important choice. When you invest, you will see two options, Direct and Regular.
The Direct Growth plan is bought straight from the fund house, without any distributor involved. Because no commission is paid out, the expense ratio is lower, meaning slightly better returns for you over the long run.
The Regular plan involves a distributor or advisor, who earns a small commission from the fund house. This commission is already built into the expense ratio, so your returns are a touch lower compared to Direct.
In my experience, if you are comfortable doing your own research or using apps like Groww and Coin, going Direct makes more financial sense. However, if you genuinely need hand-holding, paying a little extra through Regular for a good advisor isn’t a bad deal either. It depends on your comfort level.
Portfolio and Where Your Money Goes
The portfolio is mostly built around mid-cap stocks, but it isn’t restricted to only mid-caps. Roughly speaking, it holds a large chunk in mid-cap companies, with some exposure to large-cap and small-cap stocks too, to balance risk and opportunity.
This mixed approach helps the fund manager grab growth opportunities in mid caps while keeping some stability from larger, established companies. Money is spread across many sectors instead of one basket, which is generally a healthy sign.
Before investing, it’s a good habit to check the top holdings and sector allocation on the fund house website or apps like Value Research. This way, you know exactly which companies your money is going into, instead of trusting the fund name blindly.
Expense Ratio: What You Pay
The expense ratio is the yearly fee charged to manage your money. For this scheme, it is roughly 1.4% to 1.5% for the regular plan, while the direct plan usually charges less.
This might sound small, but over ten or twenty years, even a 0.5% to 1% difference can add up to a noticeable amount in your final corpus. That is exactly why many smart investors prefer the direct plan wherever they are confident managing investments themselves.
Always compare the expense ratio with other mid-cap mutual funds before deciding. A slightly higher ratio is fine if returns are consistently better, but paying more for average performance never really makes sense.
Risk Factors: Is It Risky?
Friends, let’s be honest here, because that’s the whole point of this guide. This fund carries a “Very High” risk rating as per the SEBI riskometer. Mid-cap stocks are more volatile than large caps, so prices can swing sharply in the short term.
If the market falls, mid-cap funds like this one usually fall faster and harder than large-cap funds. On the flip side, when the market rises, mid caps often rise faster too. So this scheme isn’t for someone who panics and sells at the first sign of a dip.
Clearly speaking, if you cannot handle seeing red numbers in your portfolio for months or even a year or two, this fund might give you sleepless nights. It suits investors who understand market cycles and can stay patient through rough phases.
Is It Good for Long-Term Investing?
Based on everything above, the Nippon India Growth Mid Cap Fund does look like a decent option for long-term investors who can handle short-term ups and downs. Its long history since 1995, experienced management, and consistent outperformance against its benchmark are genuinely good points in its favour.
However, this scheme is clearly not meant for short-term goals or for people who might need their money back within a year or two. Mid-cap investing works best when you give it at least five to seven years, or ideally longer, to smooth out the volatility.
If your goal is retirement planning, your child’s future, or long-term wealth creation, and you are okay with ups and downs along the way, this fund can genuinely be considered.
How to Invest, Step by Step
- Complete your KYC using PAN and Aadhaar, if you haven’t already.
- Choose a platform, either the Nippon India Mutual Fund website or apps like Groww and Zerodha Coin.
- Search for the fund by name on the platform.
- Select Direct or Regular, and Growth or IDCW, based on your preference.
- Decide between a lump sum or a monthly SIP.
- Complete payment through UPI, net banking, or auto debit for SIP.
That’s it. Within a few minutes, you can start your investment journey.
Tips for Beginners
If you are just starting, don’t jump in with a huge lump sum straightaway. Start small with a SIP, maybe ₹500 or ₹1,000 a month, and slowly increase it as you get comfortable with market movements.
Also, don’t put all your money into just one mid-cap mutual fund. It’s wiser to spread investments across large-cap, mid-cap, and maybe some debt funds too, based on your goals and risk appetite. This scheme can be a good mid-cap piece of your overall portfolio, but shouldn’t be your only investment.
Pros and Cons
Pros:
- Strong long-term track record since 1995
- Consistently beaten its benchmark over multiple years.
- Low minimum SIP amount of ₹100
- Experienced fund management team
Cons:
- Very High risk, not for nervous investors
- Not suitable for short-term financial goals
- Mid-cap volatility can be uncomfortable during market falls.
Final Thoughts
So friends, that was our honest look at the Nippon India Growth Mid Cap Fund. It has a good history, solid returns, and an easy SIP option starting at just ₹100. However, the Very High risk tag is real, and you should only invest money you won’t need urgently in the next few years.
Now let’s talk about you. If you have a long-term horizon and can stay calm during market swings, this fund is worth considering as part of a diversified portfolio. But if short-term safety is your priority, you might want to look elsewhere, or balance it out with safer options.
As always, before making any final decision, talk to a certified financial advisor who understands your personal goals and risk appetite.
FAQ's
What is the Nippon India Growth Mid Cap Fund NAV today?
The NAV changes daily with the market. As of September 2026, it is around ₹4,950 for the Direct Growth plan, so always check the live figure before investing.
What is the minimum SIP amount for this fund?
You can start a SIP with just ₹100 per month, making it accessible for beginners with limited monthly savings to build long-term wealth.
Is Nippon India Growth Mid Cap Fund good for long-term investment?
Yes, it suits long-term investors with a five- to seven-year horizon who can handle short-term volatility for potentially better returns.
What is the expense ratio of this fund?
The expense ratio is roughly 1.4% to 1.5% for the regular plan, while the direct plan charges less, improving your overall net returns.
How risky is Nippon India Growth Mid Cap Fund?
It carries a Very High risk rating as per SEBI, since mid-cap stocks are more volatile than large caps during market ups and downs.
What are the 5-year returns of this fund?
It has delivered around 20% annualised returns over the past five years, though past performance never guarantees similar future results.