Most people want to earn money even when they are not working. Imagine receiving interest from your savings, earning sales from a digital product, or getting visitors to an old blog post while you sleep. That is the basic idea behind passive income.
In India, there are several ways to build additional income alongside a job, business, or regular work. Some options require money to invest, while others require time, skills, and patience.
In this guide, we will explore five passive income ideas in India for 2026. You will learn how each method works, what you may need to get started, and the risks you should understand before choosing an option.
In This Article
ToggleHighlight key
- Passive income usually requires money, time, or effort upfront.
- PPF and fixed deposits can provide interest income, subject to their terms.
- Mutual funds and dividend stocks involve market risks.
- Digital products and blogging can generate income but require consistent effort.
- Combining different income sources may reduce dependence on a single source.
- No passive income method guarantees profits or a fixed monthly income.
What Is Passive Income?
Passive income is money earned without having to exchange your time for income every single day. For example, interest from a deposit or sales from a previously created digital product may continue without constant daily work.
However, passive income does not mean earning money without any effort.
A blog needs useful content and regular updates. Digital products require creation and marketing. Investments need research and monitoring. Even relatively hands-off income sources may require occasional attention.
The goal is to put in effort or invest money upfront so that an income source can continue generating returns over time.
1. Earn Interest Through PPF, Fixed Deposits and Savings Schemes
One of the simplest passive income ideas for beginners in India is earning interest on savings.
You can consider options such as:
- Public Provident Fund (PPF)
- Bank fixed deposits (FDs)
- Post Office Monthly Income Scheme (MIS)
- National Savings Certificate (NSC)
Each option has different eligibility rules, interest payment methods, maturity periods, and withdrawal conditions.
For example, during the October–December 2026 quarter, the PPF interest rate is 7.1% per year, while the NSC rate is 7.7%. These are scheme-specific rates and should not be treated as guaranteed rates for every savings product. Check the latest official notifications before investing.
Simple example: Suppose you deposit ₹1,00,000 in a product offering 7% annual interest. At that rate, the interest would be approximately ₹7,000 over one year, before applicable taxes and subject to the product’s terms. The actual amount may differ depending on compounding and when interest is paid.
Advantages
- Relatively predictable interest under the applicable scheme terms.
- Suitable for people who prefer lower-risk savings options.
- Some schemes may offer tax benefits, depending on eligibility and current tax rules.
Disadvantages
- Inflation can reduce the purchasing power of your returns.
- PPF has a long initial maturity period of 15 years.
- Some products have withdrawal restrictions or premature-closure penalties.
- A small investment may generate only a modest amount of income.
Who should consider it?
People who want to build savings and prefer more predictable returns may find these options useful. Remember that PPF is primarily a long-term savings product, not a regular monthly income scheme.
2. Invest in Mutual Funds Through SIPs
Mutual funds collect money from investors and invest it in assets such as shares, bonds, or other permitted securities, depending on the fund.
A Systematic Investment Plan (SIP) allows you to invest a fixed amount regularly. Some mutual funds allow investors to begin with relatively small monthly contributions, depending on the scheme.
For example, suppose you invest ₹1,000 every month through an SIP. You are building an investment portfolio over time rather than trying to generate immediate passive income.
As your investments grow, you may eventually consider withdrawing money through a Systematic Withdrawal Plan (SWP), depending on your financial goals.
However, an SIP is a method of investing, not a guaranteed income source. Mutual fund returns depend on market performance, and your investment can lose value.
An SWP also does not guarantee a fixed return or protect your original investment. Withdrawals during a market downturn can reduce the value of your remaining portfolio.
Advantages
- You can start investing with a relatively small amount in eligible schemes.
- Mutual funds provide access to professionally managed portfolios.
- Suitable funds may help investors pursue long-term financial goals.
Disadvantages
- Market-linked returns are not guaranteed.
- Equity funds can experience significant short-term declines.
- Taxes, expenses, and withdrawal timing can affect your outcome.
Who should consider it?
Investors with a long-term horizon who understand market risk may consider mutual funds as part of a diversified financial plan. Choose a fund based on your goals and risk tolerance rather than promises of high returns.
Official source: Securities and Exchange Board of India (SEBI).
Some companies distribute part of their profits to shareholders. These payments are called dividends.
If you own shares in a company that declares a dividend, you may receive money based on the number of eligible shares you hold and the dividend declared.
For example, if a company declares a dividend of ₹10 per share and you own 100 eligible shares, your gross dividend would be ₹1,000, before applicable taxes.
However, the company may reduce, skip, or stop future dividend payments. Dividends are not guaranteed.
Share prices can also fall. A company paying dividends does not automatically make its stock a safe investment.
Advantages
- Potential to receive cash payments without selling shares.
- Some established companies distribute dividends over many years.
- Dividend income can form one component of an investment portfolio.
Disadvantages
- Companies are not required to maintain the same dividend every year.
- Share prices can decline and cause investment losses.
- Dividend payments and capital gains have different tax implications under applicable rules.
Important tip: Do not choose a stock only because it has a high dividend yield. Review the company’s financial health, earnings, debt, cash flow, and dividend history.
Dividend investing is market-linked and may not be suitable for people who cannot tolerate investment losses. Consider professional advice if you are unsure how to evaluate individual stocks.
Official source: SEBI’s investor education resources and the Income Tax Department of India.
4. Sell Digital Products Online
If you have a useful skill, you may be able to turn it into a digital product and sell it online.
Unlike a physical product, a digital product can often be delivered electronically without manufacturing or shipping each order.
Examples include:
- E-books and educational guides
- Budgeting spreadsheets
- Resume templates
- Printable planners
- Online courses
- Digital illustrations and designs
For example, someone who understands personal budgeting could create a monthly expense tracker and offer it for sale.
Suppose you sell a digital template for ₹199. If customers buy it, you earn sales revenue. Your actual profit depends on the number of sales and expenses such as platform fees, advertising, refunds, and applicable taxes.
Advantages
- You can start with a skill and a relatively small budget.
- Products can be sold to multiple customers.
- You can work from home and choose your own schedule.
Disadvantages
- Creating a useful product takes time and effort.
- Competition can make it difficult to attract customers.
- Sales are not guaranteed.
- Products may need updates, customer support, and marketing.
Who should consider it?
People who enjoy writing, designing, teaching, or solving practical problems may find digital products worth exploring.
Start with one simple product that solves a specific problem. Test whether people find it useful before spending heavily on advertising or expensive tools.
5. Earn From Blogging or YouTube
Blogging and YouTube can become long-term income sources for people who consistently create useful content.
A blog may earn through advertising, affiliate marketing, sponsored content, or relevant digital products. A YouTube channel may earn through eligible monetisation features, sponsorships, affiliate links, and other permitted methods.
For example, an article explaining how to create a household budget may continue attracting visitors through search engines after publication. If the website meets the relevant requirements, those visitors may generate advertising or affiliate revenue.
However, results vary widely.
A new blog or channel may take months or longer to attract an audience. Some creators earn very little, while others build sustainable businesses. There is no guaranteed timeline or monthly income.
Advantages
- You can begin with knowledge, time, and basic equipment.
- Useful content may continue attracting visitors after publication.
- You can eventually develop multiple income sources from one audience.
Disadvantages
- Building an audience takes consistent work.
- Search traffic and video views can fluctuate.
- Advertising and affiliate income are unpredictable.
- Content needs maintenance, updates, and quality improvements.
Who should consider it?
People who enjoy writing or making videos and are willing to learn content creation, SEO, or audience development may find this option suitable.
For a finance blog, focus on accurate explanations, reliable sources, practical examples, and clear disclosures. Never promise readers guaranteed investment profits.
Quick Comparison: Which Passive Income Idea Is Right for You?
| Income Idea | Main Requirement | How You Earn | Main Risk or Limitation |
|---|---|---|---|
|
PPF and FDs |
Savings or investment capital |
Interest |
Inflation, product terms and withdrawal restrictions |
|
Mutual funds |
Investment capital and patience |
Investment growth or withdrawals |
Market losses and withdrawal risk |
|
Dividend stocks |
Capital and research |
Declared dividends |
Share-price losses and dividend cuts |
|
Digital products |
Skills and time |
Product sales |
Competition and uncertain sales |
|
Blogging or YouTube |
Time and consistent effort |
Ads, affiliate income and sponsorships |
Uncertain audience growth and income |
There is no single best option for everyone. The right choice depends on your savings, skills, time, financial goals, and ability to accept risk.
Common Passive Income Mistakes to Avoid
Before starting, avoid these common mistakes:
- Expecting instant results: Most income streams need time, effort, or capital before they produce meaningful results.
- Believing guaranteed-return promises: Be cautious of schemes promising unusually high returns with no risk.
- Ignoring taxes and expenses: Your final income may be lower after applicable taxes, fees, and other costs.
- Investing all your savings: Keep money for emergencies and essential expenses separate from long-term investments.
- Depending on a single income source: Where appropriate, different income sources may reduce dependence on one method, although diversification cannot eliminate every risk.
How to Start Building Passive Income in India
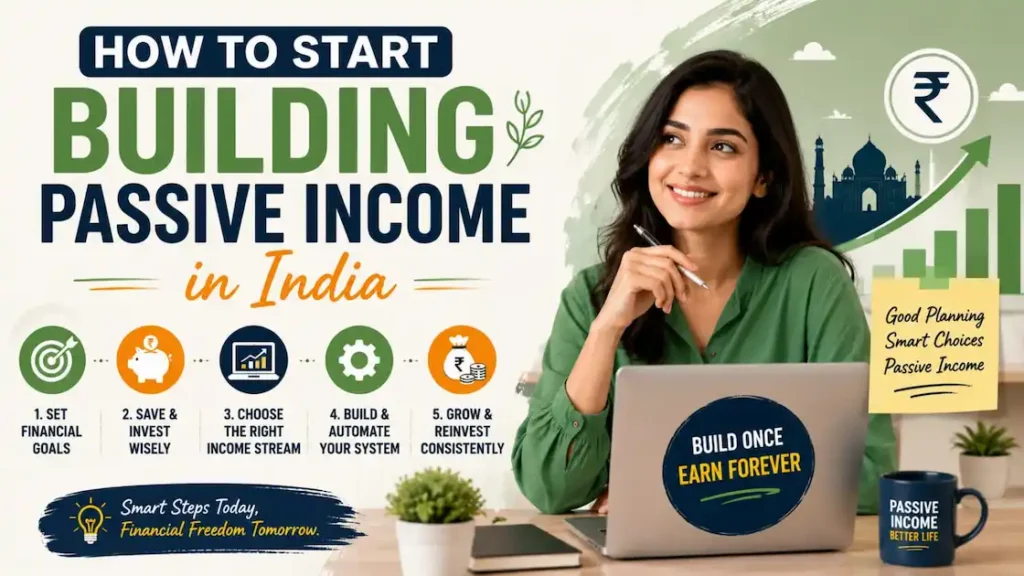
You do not need to start five income streams at once. A simple plan is often more manageable.
Step 1:
Build an emergency fund. Try to set aside enough to cover several months of essential expenses, based on your circumstances.
Step 2:
Understand your financial position. Review your income, expenses, debts, and savings before committing money.
Step 3:
Choose one suitable option. If you have savings, research suitable deposit or investment products. If you have a marketable skill, consider creating a simple digital product.
Step 4:
Start small. Avoid borrowing money or risking essential savings to pursue uncertain income opportunities.
Step 5:
Review your progress. Check your costs, returns, and workload periodically. Update your strategy as your goals change.
Over time, you may be able to develop additional income sources while keeping your financial priorities in order.
Conclusion
Passive income ideas in India can help you work towards greater financial flexibility, but they are not a shortcut to guaranteed wealth.
PPF and fixed deposits may suit people seeking interest income under defined terms. Mutual funds and dividend stocks offer investment opportunities but involve market risk. Digital products and blogging can create income opportunities for people willing to invest time and develop useful skills.
The best approach is to understand the risks, start within your means, and choose an option that fits your financial situation. Focus on building sustainable income rather than expecting overnight results.
Disclaimer: This article is for educational purposes only and does not constitute financial, investment, or tax advice. Interest rates, taxation, eligibility requirements, and product terms may change. Verify current information through official sources and consult a qualified financial professional before making investment decisions.
Article Sources
- Small Savings Interest Rates — Ministry of Finance: Department of Economic Affairs
- India Post Savings Schemes: India Post Official Website
- SEBI: SEBI Official Website
- Income Tax Department: Income Tax Department of India
- YouTube Help: YouTube Help Centre
FAQ's
What is the best passive income idea for beginners in India?
There is no single best option. Savings schemes may suit people who prefer predictable interest under applicable terms, while digital products may suit people with useful skills and limited starting capital.
Can I earn passive income with little investment?
Yes, some options require more time than money. For example, you could start creating digital products or useful online content. However, building an audience or generating consistent sales can take considerable effort.
Is passive income really passive?
Not completely. Most methods require upfront work or capital, and many need ongoing maintenance. Interest from savings products may require less regular effort, but you still need to choose a suitable product and understand its terms.
Can I earn passive income without leaving my job?
Yes. You may be able to invest regularly or build a digital product, blog, or channel alongside your job. Make sure the additional work fits your schedule and does not interfere with your essential responsibilities.
Are passive income investments risk-free?
No investment should automatically be treated as risk-free. Market-linked investments can lose value, while savings products have their own terms, limitations, and inflation risks. Understand each option before investing.
My name is Subodh Kumar, and I am a finance blogger at Financemantraa.com with a strong interest in personal finance, investing, and financial research spanning 4–5 years.
I enjoy researching financial topics and explaining complex money concepts in simple, easy-to-understand language. My areas of interest include stock market basics, IPOs, mutual funds, financial planning, insurance, saving strategies, and wealth building.
Through Financemantraa.com, I aim to help readers improve their financial knowledge, understand investment concepts, and make informed financial decisions. I focus on creating practical, beginner-friendly guides that make personal finance easier to understand and apply in everyday life.
I believe that financial education and smart money habits can help people work toward long-term financial stability. My goal is to make reliable, accessible, and informative financial content available to everyone.
Disclaimer: The information published on Financemantraa.com is for educational and informational purposes only. It should not be considered professional financial or investment advice.