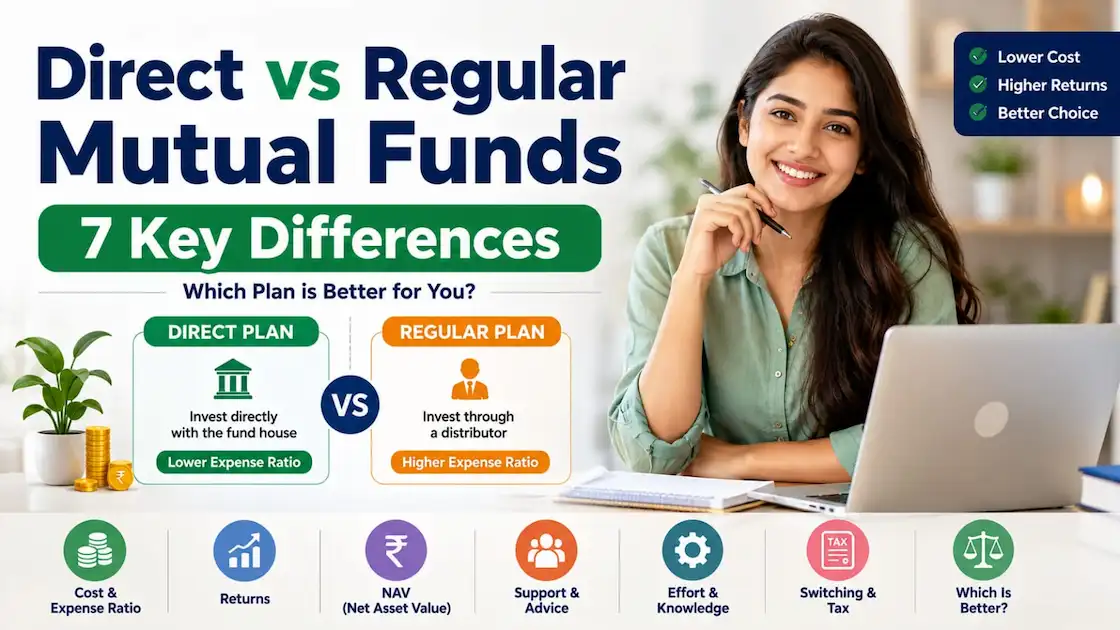
You may have seen the same mutual fund listed twice, once as “Direct Plan” and once as “Regular Plan”. Both hold the same investments, but the cost to you is different. Over many years, that gap can change your final corpus.
In this guide on direct vs regular mutual funds, we will explain the 7 key differences in simple words, with a worked example, a comparison table and the tax rules. Let’s start.
In This Article
ToggleHighlight key
- Direct and regular plans are two versions of the same scheme, with the same portfolio and fund manager.
- Regular plans include a distributor commission in the expense ratio. Direct plans do not.
- Direct plans have a lower expense ratio and a higher NAV.
- Lower cost can mean more wealth over long periods, but returns are never guaranteed.
- Switching from regular to direct means selling units, which can trigger tax and exit load.
What Are Direct Mutual Funds?
A direct mutual fund is a plan where you invest straight with the fund house (AMC), without any distributor or agent. You can do this on the AMC’s website or app, or through a platform that offers direct plans.
SEBI made direct plans compulsory alongside regular plans for every scheme from 2013. Since no commission is paid, the expense ratio is lower. morningstar
What Are Regular Mutual Funds?
A regular plan is where you invest through an intermediary, such as a mutual fund distributor, agent or bank relationship manager. Because of the distribution cost, a regular plan has a higher expense ratio. personalfn
That extra cost pays for services like fund suggestions, paperwork help and reminders.
Direct vs Regular Mutual Funds: Quick Comparison
| Point | Direct Plan | Regular Plan |
|---|---|---|
|
How you invest |
Directly with the AMC or a direct-plan platform |
Through a distributor, agent or bank |
|
Distributor commission |
None |
Included in the expense ratio |
|
Expense ratio |
Lower |
Higher |
|
NAV |
Higher |
Lower |
|
Portfolio and fund manager |
Same |
Same |
|
Long-term returns |
Usually higher, due to lower cost |
Usually lower by the cost gap |
|
Advice and support |
You manage it yourself |
Distributor may help (quality varies) |
|
Effort needed |
More |
Less |
|
Suits |
Self-learners who stay disciplined |
People who want guidance |
Direct vs Regular Mutual Funds: 7 Key Differences
Let’s compare the two plans to understand which one may suit your investment needs.
1. Distributor Commission
In a regular plan, the AMC pays your distributor a trail commission every year you stay invested. A direct plan avoids this commission. You never see it as a separate bill. It is built into the fund’s cost. morningstar
2. Expense Ratio
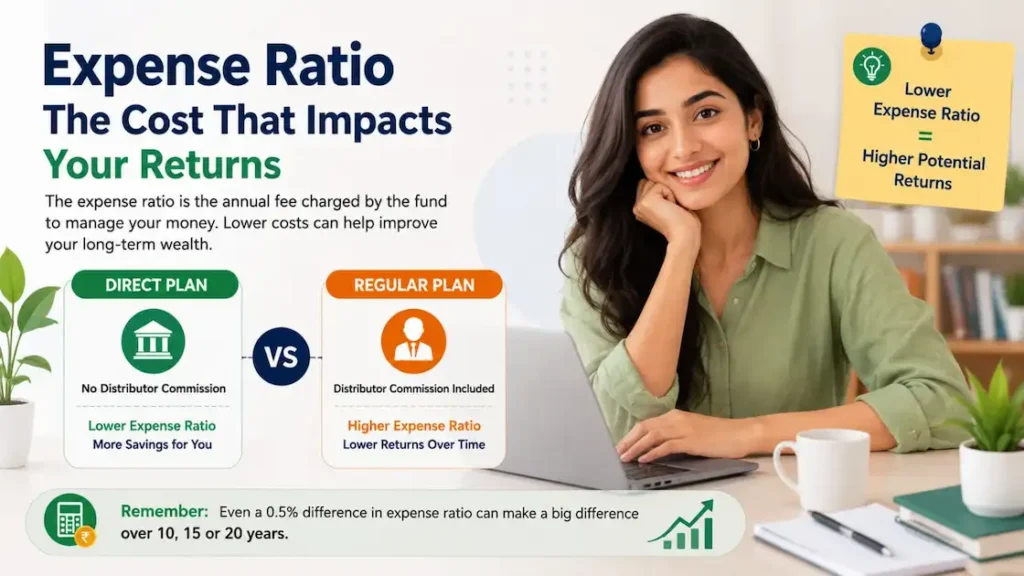
The expense ratio is the yearly fee a fund charges for running your money. It is deducted from the fund’s value, so you do not pay it separately. A regular plan has a higher mutual fund expense ratio because the commission sits inside it.
The gap differs by fund. One study of 178 diversified equity funds found an average difference of about 1.0%. Check your own scheme’s current figures on the AMC website. personalfn
SEBI’s new mutual fund regulations began on 1 April 2026. Under SEBI’s Mutual Funds Regulations, 2026, the expense framework distinguishes the Base Expense Ratio (BER) from the Total Expense Ratio (TER). The BER covers permitted scheme expenses under the applicable framework, while the TER reflects the overall applicable expense structure, including relevant additional costs and statutory levies. Investors should check the latest expense disclosures published by their fund house.
The total expense ratio is now shown as the base ratio plus permitted brokerage and statutory levies. This changes how costs are displayed. A direct plan still costs less than the regular plan of the same scheme. SEBI Mutual Funds Regulations, 2026
3. NAV (Net Asset Value)
NAV is the price of one unit. Since the direct plan has lower costs, the two plans have separate NAVs, and the direct plan’s NAV is higher. A higher NAV does not mean a costlier or better fund. The Direct Plan generally has a higher NAV than the corresponding Regular Plan because of its lower expense ratio over time.
However, a higher NAV does not mean that a mutual fund is better or more expensive. Investors should compare the scheme’s objectives, risk, costs and performance instead. AMFI — Understanding Direct Plans
4. Returns
Both plans own the same stocks or bonds, so the portfolio return is the same. The direct plan simply keeps more of it for you. This is the main point in the direct mutual fund vs regular mutual fund returns debate.
Illustrative SIP example
These are assumptions, not predictions.
- Monthly SIP: ₹10,000 for 20 years (240 months). Total invested: ₹24 lakh.
- Return before costs: 12% a year, kept constant.
- Direct plan: 12% net return.
- Regular plan: 11% net return (a 1% higher expense ratio).
- Investment is made at the end of each month. Tax, exit load and changes in expense ratio are ignored.
Formula: Future Value = P × [((1 + r)ⁿ − 1) ÷ r], where P is the monthly SIP, r is the monthly rate (yearly rate ÷ 12) and n is the number of months.
| Direct Plan | Regular Plan | |
|---|---|---|
|
Monthly rate (r) |
1% |
about 0.9167% |
|
(1 + r)²⁴⁰ |
about 10.89 |
about 8.94 |
|
Future Value |
about ₹98.9 lakh |
about ₹86.6 lakh |
|
Estimated gain |
about ₹74.9 lakh |
about ₹62.6 lakh |
For illustration, assume annualised returns after expenses of 12% for the Direct Plan and 11% for the Regular Plan. These are hypothetical assumptions, not actual fund returns or predictions. The example isolates the possible impact of a difference in net returns.
The gap is about ₹12.4 lakh, even though the fund and the market were the same. In real life, returns change every year and the cost gap can vary, so actual results will differ.
5. Advice and Support
This is where regular plans can add value. A good distributor can explain funds, link them to your goals, remind you about SIPs and keep you calm when markets fall. In a direct plan, you do all of this yourself.
Ask your distributor how they are paid, because their income depends on commission. If you want paid advice without commission, a SEBI-registered investment adviser is an option. Registered investment advisers cannot earn mutual fund commissions. upstox
6. Effort and Knowledge Needed
With a direct plan, you complete KYC, pick schemes, track performance and rebalance on your own. This is not very hard, but it needs time and interest. Regular plans save effort, but you pay for that convenience every year.
7. Switching and Tax
You can move from regular to direct, but it is not free of cost. The next two sections explain how tax works and how to switch step by step.
Tax on Mutual Funds: Equity vs Debt
Tax decides how much you actually keep, especially when you switch plans. The rules depend on the type of fund and how long you held it.
Equity-oriented funds (more than 65% in shares): short-term gains within 12 months are taxed at 20%, and long-term gains are taxed at 12.5% above ₹1.25 lakh. Resident investors face no TDS on redemption, so you calculate and pay the tax yourself when filing your return.
Debt funds: Tax treatment for debt-oriented mutual funds depends on the fund’s classification, the acquisition date and the applicable tax provisions. Certain specified mutual fund units acquired on or after 1 April 2023 are subject to special rules under which gains are generally taxed at the investor’s applicable slab rate, irrespective of the holding period. Check the current rules before redeeming or switching your investment, with no indexation. Rules for hybrid funds differ, so check your fund’s category. Income Tax Department — Capital Gains Tax Information
| Point | Equity Funds | Debt Funds |
|---|---|---|
|
Short-term period |
12 months or less |
Always short-term (units bought after 1 Apr 2023) |
|
Short-term tax |
20% |
Your income tax slab rate |
|
Long-term tax |
12.5% on gains above ₹1.25 lakh a year |
Generally not available |
|
Yearly exemption |
₹1.25 lakh on long-term gains |
None |
|
Indexation |
Not applicable |
Not available |
Budget 2025 and Budget 2026 left these mutual fund capital gains rates unchanged. Tax rules can change, so confirm them with the Income Tax Department or a tax professional. indmoney
How to Switch from Regular to Direct Mutual Funds
A switch is not a simple plan change. It is a sale of regular units, followed by a fresh purchase of direct units. Exiting a regular plan into a direct plan triggers capital gains tax. Here is the process: arthgyaan
- Confirm your plan. Check your statement. The scheme name will say “Regular” or “Direct”. Note the option too (Growth or IDCW).
- Check the cost of leaving. Find the exit load, your holding period and your estimated capital gain for each folio.
- Estimate the tax. Use the equity or debt rates above.
- Redeem the regular units. You can sell all or only part. Units are sold at the NAV of the applicable day, based on the AMC’s cut-off time.
- Invest in the direct plan of the same scheme. Use the AMC website, app or a direct-plan platform. Redemption money takes a few working days to arrive, and your money stays out of the market in between.
- Move your SIP. Stop the regular-plan SIP and start a new one in the direct plan.
- Keep records. Save the redemption and purchase statements for your tax return.
A lower-cost alternative: Keep your old regular units and put all new money into the direct plan. This avoids selling, tax and exit load. Some investors also switch in parts across financial years to use the ₹1.25 lakh long-term gains exemption on equity funds. Whether this suits you depends on your own numbers, so ask a tax professional.
Remember that the new direct units start with a fresh purchase date. Do not switch if the tax and exit load are higher than what you will save.
Advantages and Disadvantages
Direct plans
- Advantages: lower expense ratio, no commission, potentially higher long-term wealth.
- Disadvantages: no hand-holding. You are fully responsible for your decisions, including mistakes.
Regular plans
- Advantages: guidance, paperwork help and support during market stress.
- Disadvantages: higher yearly cost, and possible bias if a distributor earns more from certain funds.
Direct vs Regular Mutual Funds: Which Is Better?
For the same scheme, a direct plan costs less. That is a fact. Whether it is better for you depends on whether you can manage your own investments.
If you are comfortable researching funds and staying disciplined, a direct plan saves money. If you might panic-sell or avoid investing without help, paid guidance may be worth the cost. Either choice is valid, and this is general information, not a recommendation for any fund.
Common Mistakes to Avoid
- Choosing a fund only because its expense ratio is low. Performance, risk and your goals matter too.
- Assuming a higher NAV means a better fund.
- Moving to direct plans without understanding the fund you hold.
- Ignoring the tax and exit load on switching.
- Expecting lower costs to guarantee higher returns.
Conclusion
The main point of direct vs regular mutual funds is simple. Both plans hold the same investments, but regular plans cost more because they include distributor commission. Over 10 to 20 years, that cost can reduce your wealth by a noticeable amount. Direct plans save money but ask you to do the work. Pick the option that matches your knowledge, time and discipline, and review it from time to time.
Disclaimer: This article is for education only and is not investment, tax or legal advice. Mutual fund investments are subject to market risks. Returns shown are illustrative and not guaranteed. Expense ratios and tax rules may change, so check with the AMC, SEBI or a qualified professional.
FAQ's
What is the difference between direct and regular mutual funds?
Both invest in the same portfolio. The difference is cost. Regular plans include distributor commission in the expense ratio, while direct plans do not, so direct plans charge less and show a higher NAV.
Which is better for beginners, direct or regular?
It depends on your comfort level. Direct plans cost less but need self-management. Beginners who want guidance may prefer a trusted adviser or distributor, while self-learners can start directly.
Why do direct mutual funds have lower expense ratios?
Direct plans do not pay trail commission to distributors. With that cost removed, the plan charges only for fund management and operations, leaving a smaller yearly deduction from your investment.
How much can you save with direct mutual funds?
Savings depend on the cost gap, your amount and your holding period. A gap of around 1% a year, as in our example, can add up to several lakh rupees over 20 years, but it is not guaranteed.
How do you switch from regular to direct mutual funds?
Redeem your regular plan units, then invest in the direct plan of the same scheme. This counts as a sale, so capital gains tax and exit load may apply. Check these costs first.
Article Source
- Direct vs Regular Mutual Funds: AMFI Direct Plan Guide
- Expense Ratio and New Regulations: SEBI Mutual Funds Regulations, 2026
- Equity Mutual Fund Capital Gains: Income Tax Department — Section 112A
- General information about Capital Gains Tax: Income Tax Department Capital Gains Guide
My name is Subodh Kumar, and I am a finance blogger at Financemantraa.com with a strong interest in personal finance, investing, and financial research spanning 4–5 years.
I enjoy researching financial topics and explaining complex money concepts in simple, easy-to-understand language. My areas of interest include stock market basics, IPOs, mutual funds, financial planning, insurance, saving strategies, and wealth building.
Through Financemantraa.com, I aim to help readers improve their financial knowledge, understand investment concepts, and make informed financial decisions. I focus on creating practical, beginner-friendly guides that make personal finance easier to understand and apply in everyday life.
I believe that financial education and smart money habits can help people work toward long-term financial stability. My goal is to make reliable, accessible, and informative financial content available to everyone.
Disclaimer: The information published on Financemantraa.com is for educational and informational purposes only. It should not be considered professional financial or investment advice.