Imagine your phone rings with bad news. You get hit with an unexpected medical bill, lose your job, or need to pay for urgent home repairs. Do you have enough money right now to handle this situation, or would you need to borrow from someone?
Emergency savings play an important role in handling your and your family’s expenses during tough times.
An emergency fund is the money you save for unexpected and necessary expenses. It helps you deal with financial troubles without relying entirely on credit cards, personal loans, or long-term investments.
But how much money should you save? Is three months of savings enough, or should it be six months? And where should you invest your emergency fund to keep it safe?
In this guide, we’ll explain what an emergency fund is, how to calculate your target, where to keep your money, and seven practical steps to build a fund that helps even when your income decreases in the future.
In This Article
ToggleHighlight key
- An emergency fund covers unexpected and essential expenses.
- A common starting guideline is three to six months of essential living expenses.
- Calculate your target using monthly expenses, not your salary.
- Keep your money somewhere safe and accessible.
- Start with a small, realistic target and increase it gradually.
- Review your emergency fund whenever your financial situation changes.
What Is an Emergency Fund?
An emergency fund is a separate amount of money set aside for unexpected expenses that you cannot easily cover from your regular income.
For example, your emergency savings can help in these unexpected situations that come up in life:
- Unexpected medical expenses.
- Job loss or a sudden reduction in income.
- Urgent home or vehicle repairs.
- An essential family emergency.
- Unexpected expenses that affect your ability to cover food, rent, and other basic needs.
An emergency fund is different from money saved for planned expenses. A holiday, a new smartphone, or a festival shopping budget should normally have a separate savings goal.
The purpose of an emergency fund is simple: to protect your financial stability when life does not go according to plan.
Why Is an Emergency Fund Important?
Building an emergency fund is one of the basic steps in personal finance. This can help make many tasks easier for you.
1. Reduce Dependence on Debt
If you haven’t saved money for tough times, you might have to take out a credit card or personal loan to pay suddenly arriving bills. This can increase your financial burden through interest and other charges.
Having cash available can reduce the need to borrow.
2. Reduce Financial Stress
Unexpected expenses can be stressful, especially when your monthly income is limited. An emergency fund helps you understand the situation and prepare your next move during financial crises.
3. Protect Your Investments
Suppose you invest for long-term goals such as retirement. If an emergency occurs, you might be forced to sell investments when their market value is down.
An emergency fund can reduce the likelihood of needing to sell long-term investments at an inconvenient time.
4. Provide Support During Income Loss
Emergency savings provide financial support in situations like losing a job or a drop in business income. This lets you easily manage essential expenses until you find a new job or another source of income.
How Much Emergency Fund Do You Need?
A good financial rule is to have savings covering at least three to six months of living expenses for emergencies. However, this is not a fixed rule for everyone. Your ideal emergency fund depends on your income stability, family responsibilities, insurance coverage, and other financial commitments.
Consider these general examples:
When Is a 3-Month Emergency Fund Enough?
- You have a relatively stable income.
- Your household has more than one reliable earner.
- You have fewer financial dependents.
- You might be able to get another job in just a short time.
When Should You Save 6 Months or More?
- You are the only earner in your family.
- Your income changes from month to month.
- You run a business or work as a freelancer.
- You support children, parents, or other dependents.
- Finding another job could take considerable time.
These are general guidelines, not guarantees that a particular amount will cover every emergency.
3-Month vs. 6-Month Emergency Fund
| Factor | 3-Month Fund | 6-Month Fund |
|---|---|---|
|
Coverage |
Three months of essential expenses |
Six months of essential expenses |
|
Best suited for |
Some households with stable income |
Households needing a larger safety net |
|
Saving time |
Usually shorter |
Usually longer |
|
Main benefit |
A quicker initial target |
More support during prolonged income loss |
|
Main limitation |
May be insufficient during a long crisis |
Requires more money to build |
If you are unsure where to begin, calculate both amounts and choose a realistic first milestone. You can increase your target as your income and responsibilities change.
How to Calculate Your Emergency Fund
Calculating your emergency fund is straightforward. First, work out how much you spend each month on essential needs.
Use this formula:
Essential Monthly Expenses to Include
Essential expenses may include:
- Rent or home loan EMI.
- Groceries and basic household supplies.
- Electricity, water, and cooking gas.
- Essential phone and internet bills.
- Insurance premiums.
- Necessary loan EMIs.
- Transport costs.
- School fees and essential family expenses.
- Basic medical expenses.
You can exclude optional shopping, entertainment, holidays, and restaurant meals when calculating your basic target.
However, your final budget should reflect your actual household needs. If you have unavoidable expenses that are not covered by insurance, consider how they might affect your savings target.
Emergency Fund Calculation Example
Now let’s assume that you have to spend ₹30,000 every month on essential needs.
For three months:
₹30,000 × 3 = ₹90,000
For six months:
₹30,000 × 6 = ₹1,80,000
In this example, ₹90,000 is the three-month target, while ₹1,80,000 is the six-month target.
You can use a spreadsheet, a notebook, or an online emergency fund calculator to estimate your own target.
Remember that these figures are examples. Your actual requirement will depend on your personal circumstances.
Where Should You Keep Your Emergency Fund?
Your emergency fund should not only be safe, but also easy to use when needed when you need it. The right place depends on how quickly you may need the money and the risks you are willing to accept.
1. Savings Account
A savings account is a straightforward option for emergency money.
Advantages include:
- Convenient access to funds.
- Easy transfers and withdrawals.
- Simple account management.
Consider keeping enough money in a savings account to cover emergencies that require immediate payment.
2. Sweep-In Fixed Deposit
Some banks offer sweep-in facilities that link a savings account with a fixed deposit. Depending on the bank’s rules, money may automatically move between the accounts to meet withdrawals.
This arrangement may offer a different interest rate from an ordinary savings account, but terms, withdrawal rules, and penalties vary.
Check your bank’s conditions before using this option.
3. Liquid Mutual Funds
Some investors consider liquid mutual funds for a portion of their emergency savings. However, mutual funds are investments, not bank deposits. Their returns are not guaranteed, their value can fluctuate, and redemption may not provide immediate access in every situation.
You can read the SEBI Investor Education information on mutual funds to understand the risks.
For beginners, keeping immediate emergency money in a savings account is a simple starting point. Do not put your entire emergency fund into market-linked investments if you may need the money urgently.
What About Bank Deposit Insurance in India?
The Deposit Insurance and Credit Guarantee Corporation (DICGC) provides deposit insurance for eligible deposits in insured banks, subject to applicable rules and conditions.
The insurance limit is ₹5 lakh per depositor per insured bank, including principal and interest, for deposits held in the same right and capacity. Deposits across different branches of the same bank are aggregated for this purpose.
Read the official DICGC FAQ for details, conditions, and exclusions.
How to Build an Emergency Fund: 7 Practical Steps
Building a large emergency fund can feel difficult, particularly if you have a limited income. Instead of waiting until you have plenty of money, start with a manageable target.
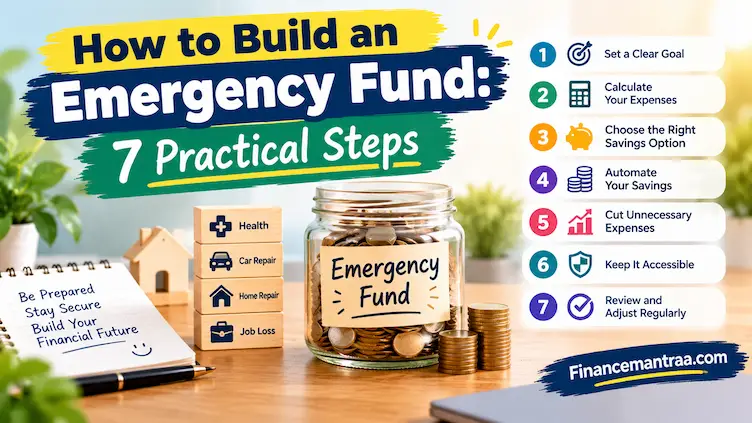
Step 1: Calculate Your Essential Expenses
Track your spending for a month. Identify the expenses you must continue paying even if your income stops.
This gives you a realistic starting point.
Step 2: Set a Clear Target
Calculate your three-month and six-month emergency fund requirements.
For example, if your essential monthly expenses are ₹20,000, your targets would be:
- Three months: ₹60,000.
- Six months: ₹1,20,000.
Choose an initial target you can realistically work toward.
Step 3: Start With a Small Goal
You do not need to save the entire amount immediately.
Your first milestone could be ₹5,000, ₹10,000, or one month’s essential expenses, depending on your income and household needs.
The important thing is to begin building the habit.
Step 4: Keep the Money Separate
Use a separate savings account or another suitable arrangement for your emergency fund.
Keeping it separate from your everyday spending money can help you avoid using it for unnecessary purchases.
Step 5: Automate Your Savings
If possible, schedule a transfer to your emergency savings account shortly after you receive your salary or other regular income.
Even a small, consistent contribution can help you make progress.
Step 6: Review Your Spending
Look for expenses you can reduce without affecting essential needs.
For example, you might cancel unused subscriptions, reduce unnecessary purchases, or compare service plans.
You do not need to eliminate every small pleasure. Choose changes that are realistic and sustainable.
Step 7: Save Extra Income
When you receive a bonus, a refund, a gift, or additional income, consider putting a portion toward your emergency fund.
Once you reach your first milestone, continue building toward your longer-term target.
How to Save for an Emergency Fund on a Low Income
When a big part of your income goes into essential expenses, saving money isn’t easy. But an emergency fund built up little by little can provide financial support during tough times.
Here are a few practical ideas:
- Start small: Save an amount you can afford, even if it is only ₹500 a month.
- Save weekly: Smaller weekly contributions may feel easier than one large monthly transfer.
- Set a starter target: Aim for a manageable amount before working toward three to six months of expenses.
- Use extra income carefully: Put part of occasional additional income toward savings when possible.
- Review your budget: Look for expenses you can reduce without sacrificing essential needs.
- Increase contributions gradually: If your income rises, consider increasing your savings amount.
For example, saving ₹500 every month adds up to ₹6,000 over 12 months, excluding any interest. This may not cover every emergency, but it is a useful starting point.
If your essential expenses are higher than your income, focus first on a realistic budget, available support, and improving your financial position. Do not feel pressured to meet an unrealistic savings target.
Should you put money into an emergency fund before investing?
For many people, building some emergency savings before investing heavily is a sensible approach.
Without an emergency fund, an unexpected bill may force you to borrow money or sell investments at an inconvenient time.
How much savings you need before starting to invest depends on your financial situation and needs. In every case, it’s not necessary to save six months’ expenses.
One possible approach is to:
- Build a small starter emergency fund.
- Address high-interest debt and essential financial obligations.
- Continue building emergency savings while considering suitable long-term investments.
- As your income and responsibilities change over time, make sure to adjust your financial plan too.
When your income or responsibilities change, make sure to update your plan accordingly.
The right balance depends on your circumstances, including your existing savings, debt, income stability, and financial goals.
Remember that investments can involve risk. Read the SEBI Investor guidance on investment decisions before making investment choices.
Common Emergency Fund Mistakes to Avoid
Strengthen your emergency fund and avoid these mistakes:
- Saving based on income instead of expenses: Calculate your target using essential monthly costs.
- Using the money for non-emergencies: Keep planned purchases and holidays separate from emergency savings.
- Taking unnecessary investment risks: Avoid placing money you may need urgently into volatile assets.
- Forgetting to replenish the fund: If you use emergency savings, rebuild them when your financial situation allows.
- Waiting for the perfect amount: Start with a manageable target rather than postponing saving indefinitely.
- Never review your target: Increase your savings goal if your living costs, family responsibilities, or financial commitments rise.
Conclusion
Emergency savings come in handy during unexpected expenses. It reduces dependence on loans and can help prevent your future financial goals from being affected.
Start by calculating your essential monthly expenses. Then choose a realistic target, such as three to six months of those expenses, based on your income stability and family responsibilities.
Keep your money somewhere suitable, safe, and accessible. Begin with a small amount if necessary, save consistently, and increase your target gradually.
Don’t wait for a special time to start saving. Begin setting aside money as soon as your budget allows. Small but regular savings can help you reach your goals over time.
Disclaimer: This article is for educational purposes only and does not constitute personalised financial advice. Savings products, bank terms, and investment risks vary. Verify current conditions with the relevant financial institution or official source before making financial decisions.
Article Sources
- DICGC Official FAQ — Insurance rules for eligible bank deposits in India and the ₹5 lakh limit.
- SEBI Investor Education: Mutual Funds — Risks associated with mutual funds and investment basics.
- SEBI Investor: Factors to Consider Before Investing — The importance of risk, liquidity, and financial goals in investment decisions.
FAQ's
ow much money should I save in an emergency fund?
A common guideline is three to six months of essential living expenses. Calculate your monthly needs and multiply them by three or six. You may need a larger fund if your income is irregular or you support dependents.
ow many months of expenses should an emergency fund cover?
Three to six months is a common starting guideline. The right amount depends on your job stability, household responsibilities, insurance coverage, and access to other reliable sources of money.
How much emergency fund should a beginner have?
A beginner can start with a manageable amount, such as ₹5,000, ₹10,000, or one month’s essential expenses. Choose a target that suits your financial situation and increase it gradually.
Where should I keep my emergency fund?
A savings account is a straightforward option for money you may need immediately. You can also consider a sweep-in fixed deposit after checking the bank’s withdrawal rules and charges. Market-linked investments carry risks and may not be suitable for money you need urgently.
What counts as an emergency?
An emergency is an unexpected and necessary expense, such as a medical bill, job loss, or urgent repair. Planned spending, such as holidays and shopping, should generally be covered by separate savings.
My name is Subodh Kumar, and I am a finance blogger at Financemantraa.com with a strong interest in personal finance, investing, and financial research spanning 4–5 years.
I enjoy researching financial topics and explaining complex money concepts in simple, easy-to-understand language. My areas of interest include stock market basics, IPOs, mutual funds, financial planning, insurance, saving strategies, and wealth building.
Through Financemantraa.com, I aim to help readers improve their financial knowledge, understand investment concepts, and make informed financial decisions. I focus on creating practical, beginner-friendly guides that make personal finance easier to understand and apply in everyday life.
I believe that financial education and smart money habits can help people work toward long-term financial stability. My goal is to make reliable, accessible, and informative financial content available to everyone.
Disclaimer: The information published on Financemantraa.com is for educational and informational purposes only. It should not be considered professional financial or investment advice.